Skip to main content
Monday–Friday · 9:00 AM – 5:00 PM ET·independent · Insuring businesses nationwide

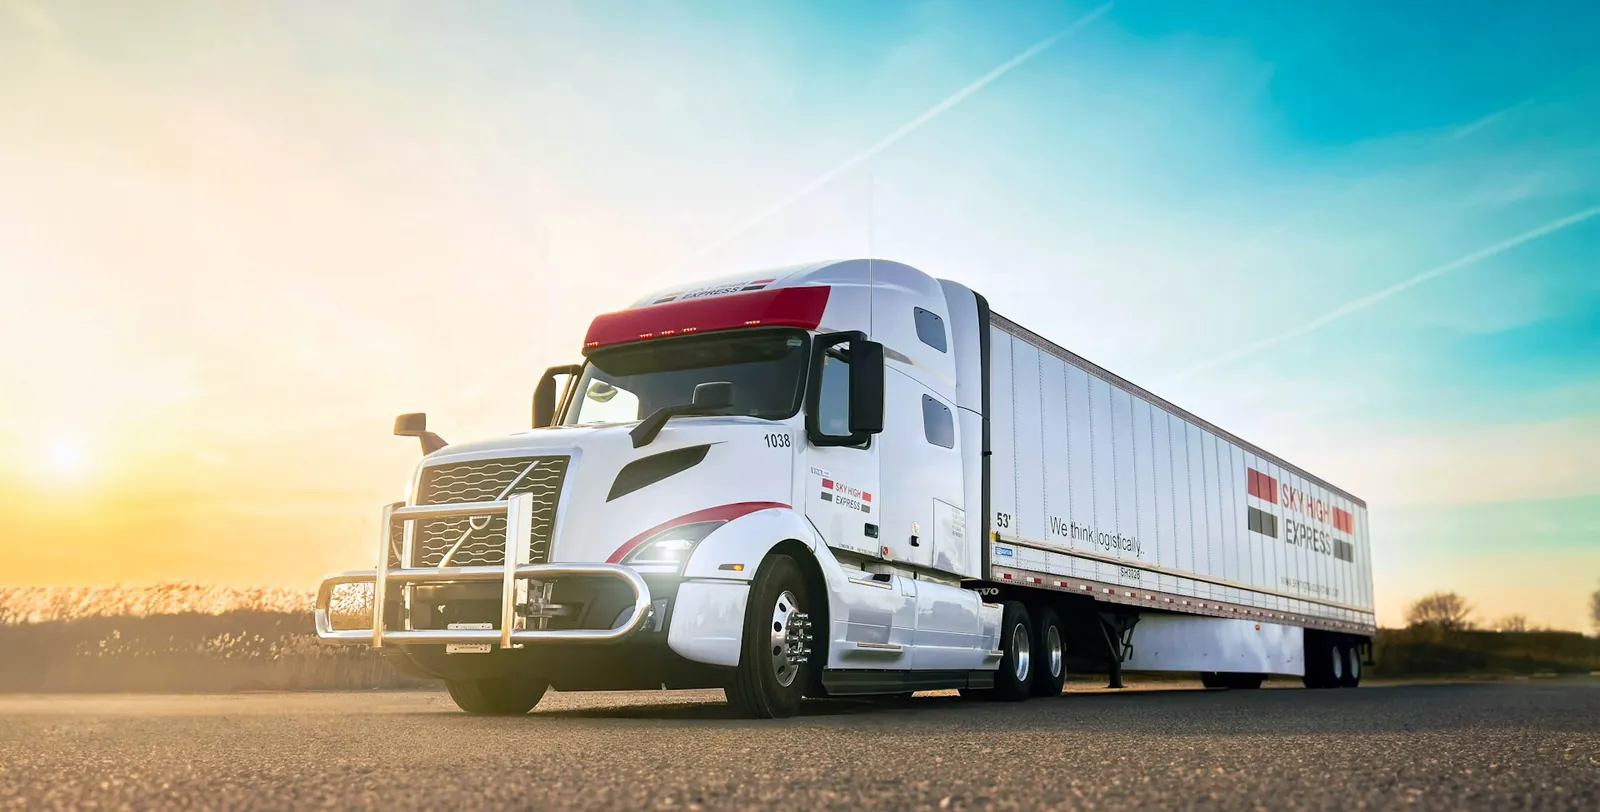
Trucking · Motor Truck Cargo
Motor Truck Cargo Insurance — coverage for the freight you haul
Motor truck cargo insurance helps owner-operators and fleets protect the freight they haul, from grain and general freight to refrigerated loads. Ellie shops multiple insurance markets for competitive quotes and helps you compare limits, endorsements, and contract requirements for your operation.
Coverage
What this trucking program covers
- Cargo limit
Per-conveyance limit covers freight in transit; sub-limits often apply to commodities and theft.
- Reefer breakdown
Endorsement covers loss from refrigeration unit failure — not automatic.
- Debris removal
Cleanup costs after an accident; usually 25% of the cargo limit.
- Earned freight
Lost freight charges when cargo is destroyed.
- Pollution cleanup
First-party cleanup for spills from cargo (limited).
Federal authority and the right insurance filings sit underneath all of this. If you run interstate, see how FMCSA filings and financial-responsibility rules (MCS-90, BMC-91/91X, BOC-3, and UCR) tie into the coverage above.
Common gaps
What it typically won't cover
- Cargo theft past sub-limit (typically $25K–$100K)
- Reefer breakdown without endorsement
- Improperly secured cargo (49 CFR Part 393 failures)
- Money, securities, jewelry, or precious metals
- Live animals and hazardous materials without specific schedule
- Loading and unloading damage (general liability concern)
Illustrative loss scenarios
Where coverage questions arise
These examples illustrate exposures, not actual Ellie claims or guarantees of payment. The policy terms and loss facts determine whether a claim is covered.
Reefer failure spoils a perishable load
A refrigeration unit fails overnight and a full produce load arrives spoiled. Cargo responds only if the reefer-breakdown endorsement is in place; the base cargo form excludes mechanical refrigeration failure.
Cargo theft from a truck stop
A trailer of electronics is stolen from an unsecured lot. Cargo pays up to the theft sub-limit — often far below the load value — so a higher theft endorsement is what protects high-value freight.
Accident with debris cleanup
A rollover scatters freight and packaging across the highway. The cargo policy's debris-removal provision (commonly 25% of the limit) covers cleanup costs the auto policy won't.
Pricing
What drives this premium
Commodity hauled
General freight cheapest; electronics, alcohol, and refrigerated load premium.
Limit selected
$25K–$100K most common; $250K+ for high-value or contract-required limits.
Operating radius
Long-haul rates higher than local or regional.
Loss history
Cargo claims drive cargo premium more than auto premium.
Scheduled vs blanket
Scheduled rates individually; blanket sets one rate for all commodities.
Theft endorsement
Required for high-theft commodities; usually adds 10–25% to premium.
Understand the differences between vehicles and operations in our truck insurance cost guide by vehicle for liability, cargo, physical damage and the choices affecting your own cost.
Filings & compliance
Authority and insurance filings come first
For most general-freight carriers, motor truck cargo insurance is a business or contract requirement rather than a federal cargo filing. FMCSA requires cargo proof (BMC-34 or BMC-83) for household-goods authority; public-liability filings such as BMC-91/91X are separate and depend on your authority and operation. Check your FMCSA registration and state rules rather than assuming a filing applies. We confirm what your contracts and authority demand.
Read the FMCSA filings guideGetting started
Start an insurance conversation
Start an insurance conversation
Start with your business and contact details. You do not need every document ready to reach out; your agent will explain which additional information is relevant to your coverage.
- Power unit count and commodity mix
- Average and maximum load value
- Operating radius and primary lanes
- Refrigerated requirements (if any)
- Five-year cargo loss history
- Shipper/broker contract limit requirements
Related programs
Other trucking programs we write
Run a mixed fleet or a different unit? We place every major motor-carrier class across 100+ markets.
Semi-Truck
OTR and regional Class 8 tractor-trailer programs.
Learn more
Box Truck
Straight trucks for local delivery, moving, and last-mile freight.
Learn more
Dump Truck
Aggregate, debris, and construction hauling with on-site exposure.
Learn more
Flatbed
Open-deck freight with load-securement and tarping exposure.
Learn more
Hot Shot
Expedited loads on 1-ton duals and gooseneck trailers.
Learn more
See the full lineup on the trucking insurance hub.
FAQ
Frequently Asked Questions
- Not by law for most operations, but contractually required by nearly every shipper and broker. Motor truck cargo is the standard coverage.
- Scheduled rates each commodity individually and is best when you haul predictable freight. Blanket sets one rate for everything you haul and is best for mixed freight.
- No — refrigeration breakdown requires a specific endorsement. Without it, claims from temperature excursions are typically denied.
- Theft sub-limits of $25K–$100K are common. High-value or high-theft commodities require itemized scheduling.
- A loading or unloading loss can involve different coverages. Cargo insurance may respond to damage to the freight if the form covers that stage of transit; general liability may respond to a third party's injury or property-damage claim. Check the cargo form, who had custody, the loading agreement, and any trailer or warehouse exposure before treating either policy as the answer.
Keep reading
Explore related coverage
Trucking Hub
All programs and core lines for motor carriers.
FMCSA Filings
MCS-90, BMC-91/91X, BOC-3, UCR, and authority explained.
Cost by Vehicle
Vehicle use and coverage choices that change insurance cost.
Motor Truck Cargo
Cargo coverage by commodity.
Non-Trucking Liability
Liability questions for qualifying personal, nonbusiness use.
Commercial Auto
Auto liability fundamentals.
Workers' Compensation
WC for company drivers.
Sources
Authoritative references
- FMCSA — Insurance / Financial Responsibility Requirements
- III — Business Vehicle Insurance (Insuring Your Business)
- IRMI — Insurance Glossary
Coverage descriptions and regulatory figures on this page are general summaries reviewed against the references above and are not a statement of coverage, legal advice, or a guarantee of eligibility or price. Last reviewed . Requirements and policy terms change — always confirm current rules with the relevant agency and verify coverage against the actual policy and a licensed agent.
Carrier access
More insurance options. One agency in your corner.
With access to 100+ carrier markets, we do the shopping so you don’t have to contact each company yourself. Your Ellie agent helps you compare competitive quotes and choose insurance for the work you do.
+75 more
Next step
Let's find insurance for your business
Tell us about your business. We’ll shop our insurance markets for competitive quotes and help you compare coverage, price and the support you need from your agency.