Skip to main content
Monday–Friday · 9:00 AM – 5:00 PM ET·independent · Insuring businesses nationwide
Trucking · Semi-Truck
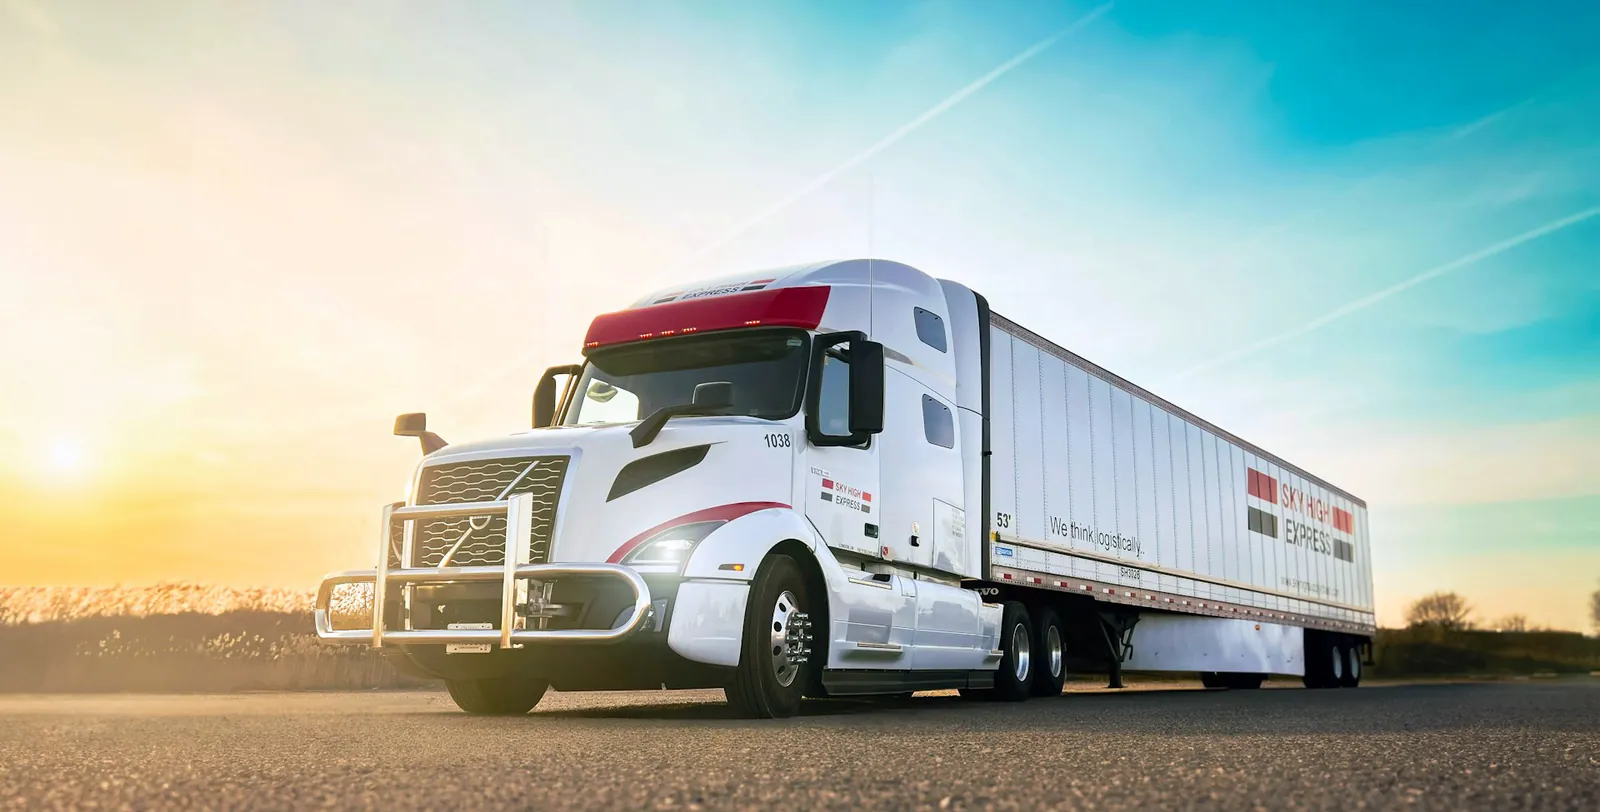
Semi-Truck Insurance — OTR and regional tractor-trailer programs
Semi-truck insurance covers Class 8 tractors and trailers running interstate or intrastate freight. We place primary liability, physical damage, motor truck cargo, NTL, and trailer interchange — and we handle MCS-90 and Form E filings so your authority stays in good standing.
At a Glance
- Liability typical
- $1M CSL
- Cargo typical
- $100K – $250K
- Physical damage
- ACV or stated value
- Filings
- MCS-90 / Form E / BOC-3
Quick answer
Ellie Insurance Group is an independent business insurance agency headquartered in Tampa, Florida that shops 100+ carrier markets to review semi-truck insurance needs for motor carriers and owner-operators. Commercial auto liability, physical damage, and motor truck cargo address different exposures; filings and federal financial responsibility depend on the operation and authority. A licensed agent can review your trucks, drivers, cargo, and lanes to discuss available options.
Coverage
What this trucking program covers
- Primary liability
$750K FMCSA minimum for general freight; $1M industry standard.
- Physical damage
Collision + comprehensive on tractor and trailer.
- Motor truck cargo
By commodity, with refrigeration breakdown when applicable.
- Non-trucking liability (bobtail)
Covers liability when the truck is off-dispatch or empty between contracts.
- Trailer interchange
Liability for non-owned trailers under written interchange agreement.
- MCS-90 / Form E
Federally-required filings for interstate operating authority.
Federal authority and the right insurance filings sit underneath all of this. If you run interstate, see how FMCSA filings and financial-responsibility rules (MCS-90, BMC-91/91X, BOC-3, and UCR) tie into the coverage above.
Common gaps
What it typically won't cover
- Owner-operator personal-use accidents (without NTL)
- Cargo theft past sub-limit
- Unattended-vehicle theft (without endorsement)
- Reefer breakdown (without breakdown endorsement)
- Hazardous materials beyond declared commodity
Illustrative loss scenarios
Where coverage questions arise
These examples illustrate exposures, not actual Ellie claims or guarantees of payment. The policy terms and loss facts determine whether a claim is covered.
Rear-end collision, loaded
A tractor-trailer running I-75 fails to stop in slowing traffic and rear-ends a passenger vehicle. Primary auto liability responds to bodily injury and property damage; the MCS-90 backstops payment if a coverage dispute arises on an interstate load.
Jackknife and cargo loss
Wet pavement and a panic stop jackknife the rig, damaging the trailer and spilling freight. Physical damage covers the tractor and trailer; motor truck cargo pays for the lost commodity up to the scheduled limit.
Off-dispatch parking-lot accident
An owner-operator drives the bobtail tractor to dinner and hits a parked car. The primary policy may deny because the unit was off-dispatch; non-trucking liability is what responds here.
Pricing
What drives this premium
Radius & routes
Long-haul loaded (500+ miles) rates higher than regional or local.
Driver MVRs
DUIs and serious violations in the last 3 years move you to E&S markets.
Equipment value
Newer Peterbilts, Kenworths, and Volvos rate cheaper for physical damage than older units.
Commodities
Refrigerated and high-theft commodities (electronics, alcohol) load cargo premium.
Loss history
Three years of clean loss runs unlock preferred markets.
Years in business
New ventures pay 30–60% more for the first 12 months.
Want a realistic budget before you quote? See typical Florida truck insurance cost ranges by vehicle for primary liability, cargo, and full-program estimates across every equipment type.
Filings & compliance
Authority and insurance filings come first
Class 8 interstate carriers must keep an MCS-90 endorsement and BMC-91/91X public-liability filing on file for FMCSA financial responsibility, plus BOC-3 process agents and current UCR. We file these and monitor them so a lapse never deactivates your authority.
Read the FMCSA filings guideQuote checklist
What we'll need to quote
Quote checklist
What we'll need to quote
- MC and DOT numbers, plus authority status
- Driver list (DL, DOB, hire date) and MVRs
- Power unit + trailer schedule with VINs
- Commodities, lanes, and annual mileage per unit
- Five-year loss runs
- Current declarations pages
Related programs
Other trucking programs we write
Run a mixed fleet or a different unit? We place every major motor-carrier class across 100+ markets.
Box Truck
Straight trucks for local delivery, moving, and last-mile freight.
Learn more
Dump Truck
Aggregate, debris, and construction hauling with on-site exposure.
Learn more
Flatbed
Open-deck freight with load-securement and tarping exposure.
Learn more
Hot Shot
Expedited loads on 1-ton duals and gooseneck trailers.
Learn more
Cargo Van
Sprinter and cargo-van couriers, expediters, and last-mile carriers.
Learn more
See the full lineup on the trucking insurance hub.
FAQ
Frequently Asked Questions
- No — most cargo policies exclude refrigeration breakdown unless specifically endorsed. Ask for the breakdown endorsement if you haul perishables.
- Trailer interchange covers liability for non-owned trailers under a written interchange agreement. Without one, your auto liability may exclude damage to trailers you pull.
- Scheduled lists specific commodities and rates them individually; blanket sets one rate for everything you haul. Brokers often require scheduled limits for high-value loads.
- Generally no — MCS-90 is a federal endorsement tied to FMCSA financial responsibility rules for interstate carriers. Florida-only carriers follow § 627.7415 minimums.
- $750,000 per occurrence for interstate carriers of general freight. Hazmat carriers require $1M–$5M depending on commodity.
Keep reading
Explore related coverage
Trucking Hub
All programs and core lines for motor carriers.
FMCSA Filings
MCS-90, BMC-91/91X, BOC-3, UCR, and authority explained.
Cost by Vehicle
Florida truck insurance price ranges by vehicle and operation.
Motor Truck Cargo
Cargo coverage by commodity.
Non-Trucking Liability
Liability questions for qualifying personal, nonbusiness use.
Commercial Auto
Auto liability fundamentals.
Workers' Compensation
WC for company drivers.
Sources
Authoritative references
- FMCSA — Insurance / Financial Responsibility Requirements
- III — Business Vehicle Insurance (Insuring Your Business)
- IRMI — Insurance Glossary
Coverage descriptions and regulatory figures on this page are general summaries reviewed against the references above and are not a statement of coverage, legal advice, or a guarantee of eligibility or price. Last reviewed . Requirements and policy terms change — always confirm current rules with the relevant agency and verify coverage against the actual policy and a licensed agent.
Carrier access
Access to 100+ A-rated commercial markets
As an independent agency we shop 100+ admitted and surplus-lines carrier markets — so the carrier competes for your business, not the other way around.
+75 more
Next step
Ready to shop commercial coverage?
Start an instant quote or speak with a commercial agent. We'll review available markets and the carrier's requirements before coverage can be bound.