Skip to main content
Monday–Friday · 9:00 AM – 5:00 PM ET·independent · Insuring businesses nationwide

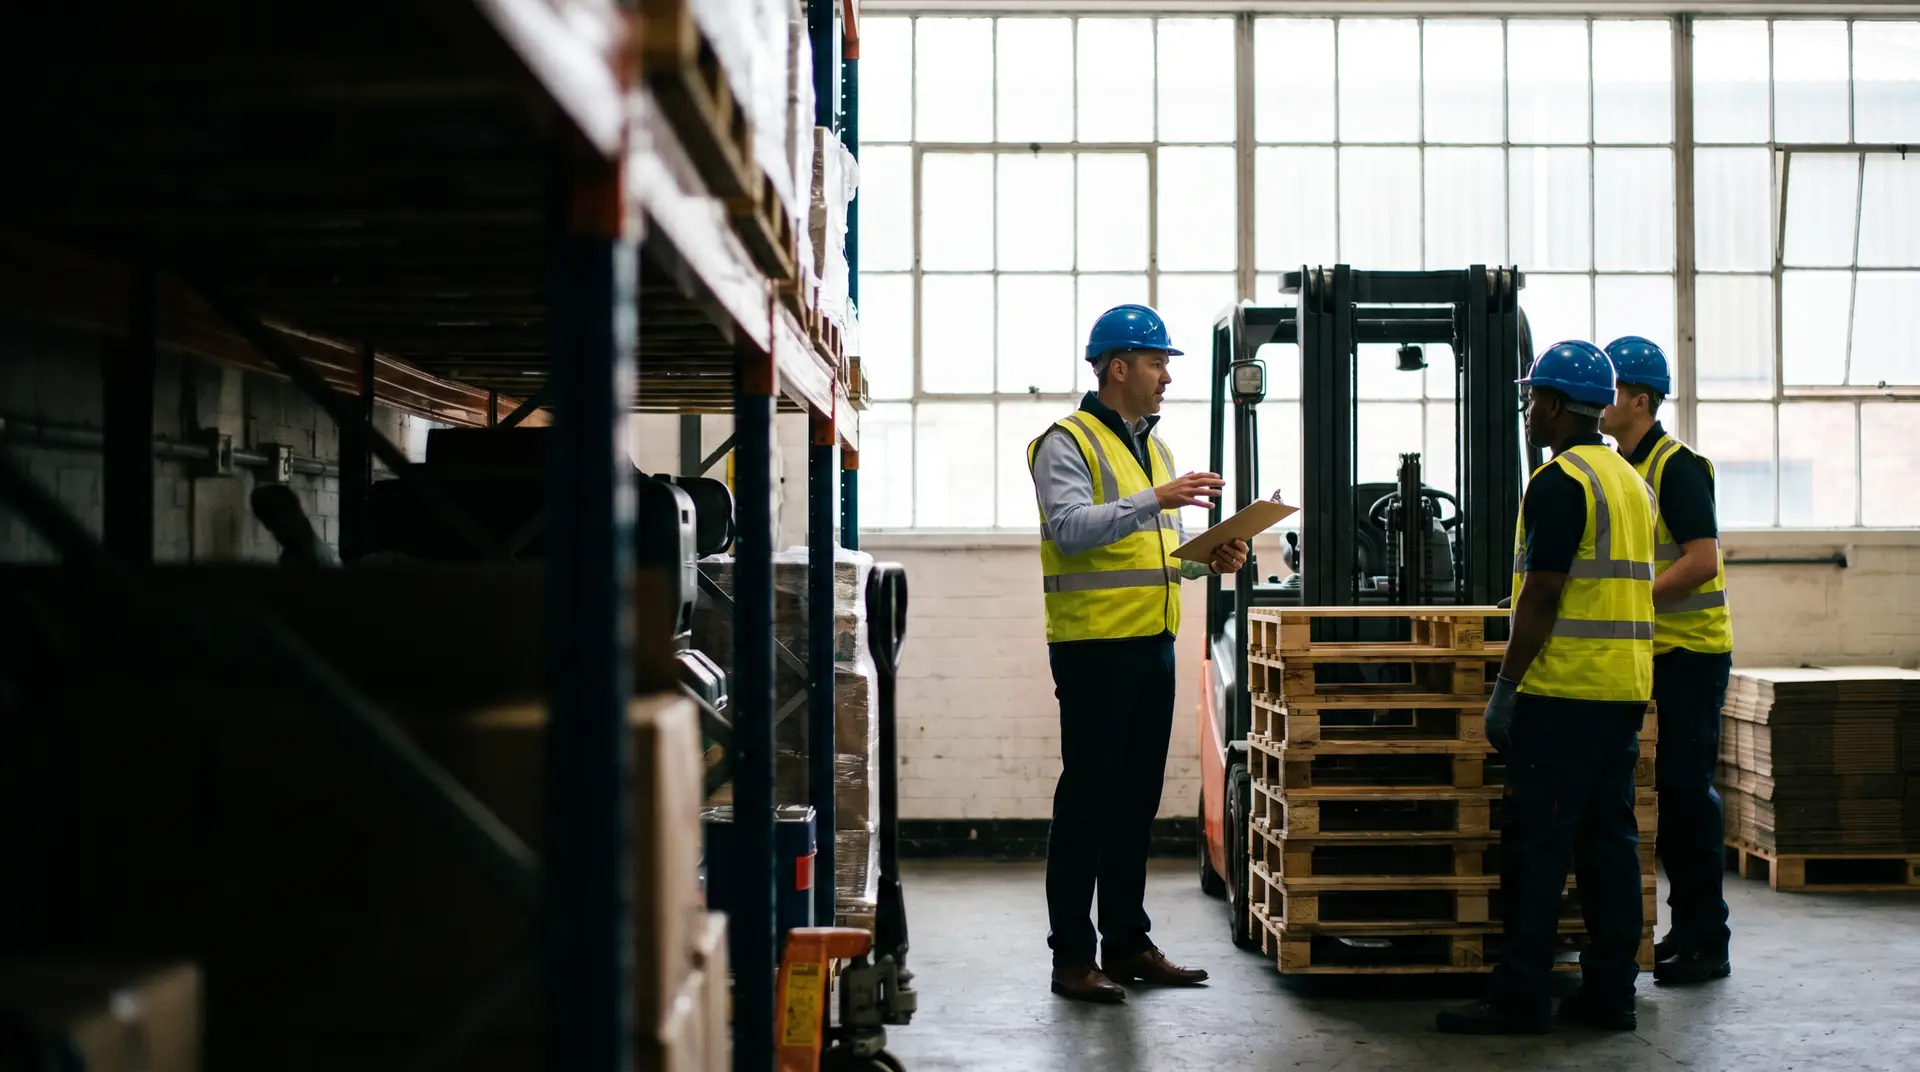
Workers' Compensation Insurance for Florida Businesses
Workers' compensation, matched to your business and the work your team does.
Protect your employees and keep your Florida business moving with workers' compensation insurance. Ellie helps contractors, restaurants, service businesses, and other employers compare competitive quotes and choose coverage that fits their payroll and job duties.
Who needs this
Who needs workers' compensation in Florida
Florida construction employers (1+ employees)
Construction employers generally need workers' compensation in Florida when they have one or more employees, including some scenarios involving certain owners and officers.
Florida non-construction employers (4+ employees)
Non-construction employers in Florida usually need coverage at four or more employees, with full-time and part-time workers counted toward the threshold.
Subcontractors and independent contractor reviews
A worker labeled a subcontractor may still be treated as an employee under workers' compensation rules. Florida has detailed independent contractor tests and uninsured subs can become the hiring contractor's payroll on audit.
Restaurants and hospitality
Service industry payroll is rated separately from kitchen and management. Split correctly, the premium can be more accurate at audit.
Healthcare, home services, manufacturing, warehousing
Each industry has its own classification codes, exposures, and expected loss patterns that drive insurer eligibility and pricing.
Owners considering an exemption
Florida allows certain construction industry owners to file an exemption with the state. Exemption rules are specific and should be reviewed before assuming they apply.
What it covers
What Workers' Comp actually covers
- Medical treatment for injured employees
For a compensable injury, Florida requires medically necessary treatment, care, and attendance, subject to the law’s treatment rules and limits. The fee schedule governs provider reimbursement; it does not make every service or claim automatically payable.
- Lost wages (indemnity benefits)
A percentage of lost income while the employee recovers and cannot work, subject to state-specific waiting periods and caps.
- Permanent partial / total disability
Florida may pay impairment or permanent-total disability benefits after a compensable injury, but eligibility, amount, and duration depend on the statutory test, medical status, and ability to perform work—not simply whether the employee can return to the prior job.
- Vocational rehabilitation
Retraining and job-placement services for employees unable to return to their pre-injury role.
- Death benefits to surviving dependents
Funeral expenses and ongoing benefits to dependents in the event of a fatal workplace accident.
- Employer's Liability (Part Two)
Defense for lawsuits arising from the injury beyond statutory WC — third-party-over claims, loss of consortium, and dual-capacity claims.
What it doesn't cover
What WC won't cover
- Injuries that occur outside the scope of employment
- Self-inflicted injuries and injuries from intoxication or drug use (per state)
- Injuries during commuting (with limited exceptions)
- A contractor must obtain required evidence that each subcontractor has secured workers’ compensation before work starts. Without it, the contractor can be responsible for benefits for that subcontractor’s workers.
- Stress, mental, or stress-only claims in many states
- Claims involving employee misconduct or fighting (per state)
- Punitive damages in many jurisdictions
- General liability — bodily injury to non-employees (covered by GL)
Cost drivers
What drives WC pricing
Class codes
The single biggest lever. Office and clerical class codes carry much lower rates than high-hazard trades like roofing or framing — the spread between the lowest and highest WC class codes is dramatic.
Total payroll
A starting estimate applies the rate for each approved work classification to payroll. An eligible experience-modification factor and other carrier or state rating elements can change the result; final premium uses actual payroll and classifications.
Experience mod (e-mod)
For an employer eligible for experience rating, the mod compares incurred losses and payroll with similarly classified employers. It commonly reflects prior policy periods rather than the current term and can be revised; ask for the current worksheet and review its employer, classifications, and loss data.
State
WC is state-rated. Florida, Georgia, and Texas all use different rate filings and rules.
Loss history
Frequency hurts more than severity. Three clean years materially help renewals.
Safety program and OSHA history
Documented safety programs unlock schedule credits with most carriers.
Start an insurance conversation
Start with your business and contact details. You do not need every document ready to reach out; your agent will explain which additional information is relevant to your coverage.
- Legal entity, FEIN, and years in operation
- Operations description and trades performed
- Projected payroll by class code / role
- Owner/officer count and inclusion preferences
- Three years of loss runs (or prior WC declarations)
- Current experience mod worksheet, if applicable
- Sub-contractor usage and certificate practices
- State(s) of operation and primary office location
Need workers' comp for your Florida business or job site?
FAQ
Frequently Asked Questions
- Workers' compensation generally covers medical care, lost wages, and certain disability or rehabilitation benefits when an employee is injured or becomes ill due to work. It also typically includes employer's liability coverage for certain related lawsuits. Coverage and amounts are governed by state law, including Florida statutes and Workers' Compensation Joint Underwriting Association rules.
- In Florida, construction employers usually need workers' compensation when they have one or more employees, and non-construction employers when they have four or more. Owner status, contractor classification, and certain industries can shift the analysis. Out-of-state employers with workers in Florida should review whether Florida coverage applies before sending workers across the border.
- Workers' compensation usually does not cover claims unrelated to work, intentional self-injury, certain horseplay or rule violations, third-party bodily injury or property damage, business vehicle physical damage, or general liability claims. Some states allow narrow exceptions for serious employer misconduct, but workers' compensation is not a substitute for general liability, commercial auto, or professional liability.
- Pricing is based on payroll by job duty, classification codes, the experience modification factor, and state rules. Carriers also consider safety records, prior claims, subcontractor controls, and industry. The mod compares actual losses to expected losses for similar businesses, so several years of loss-free operation can lower it while serious or repeated claims can raise it.
- Ellie typically needs the legal business name, federal employer identification number, ownership details, operations description, locations, employee count, payroll by job duty, prior carriers, and recent loss runs. Construction employers may need to share subcontractor controls and project descriptions. The more accurate the payroll, the more reliable the quote will be at audit.
- Yes. The agency works with access to 100+ carrier markets, which can be useful when classification, prior losses, payroll size, or industry creates challenges. Not every carrier writes every business, but broader access can help business owners avoid relying on one option.
- Yes. Ellie Insurance Group serves businesses in Tampa, Brooksville, and across Florida, where employer requirements depend on industry and employee count. The agency is also licensed in TX, NC, SC, GA, NM, and UT for owners with workers in more than one state.
Keep reading
Explore related coverage
General Liability
Pairs with WC on most commercial accounts.
Contractor Insurance
Coverage options for contractors managing multiple trades and subcontractors.
WC Audit Help
Dispute support when the audit doesn't match payroll.
Workers' Comp Cost Guide
How class codes, mods, and payroll caps drive the rate.
Quote Center
Share your business details to compare workers' comp options.
Restaurants Insurance
Restaurant payroll and tip handling done correctly.
Sources
Authoritative references
- IRMI — Workers Compensation (definition)
- U.S. Department of Labor — Workers' Compensation
- Florida CFO — Division of Workers' Compensation
Coverage descriptions and regulatory figures on this page are general summaries reviewed against the references above and are not a statement of coverage, legal advice, or a guarantee of eligibility or price. Last reviewed . Requirements and policy terms change — always confirm current rules with the relevant agency and verify coverage against the actual policy and a licensed agent.
Related articles
Deeper reading on this coverage
Cost benchmarks
Workers' Compensation Insurance Cost: What Drives the Rate
How estimated workers’ compensation premium becomes final premium, how classifications work, and what to review at audit.
Workers' comp
Workers’ Comp Audit Guide: Understand, Prepare, and Question an Audit
How workers’ comp audits work, which records help, and how to request a correction when something looks wrong.
Coverage guidance
Workers' Comp Class Codes: How They Affect Your Premium
How workers’ comp class codes work, what can prompt a review, and which records help clarify the work performed.
Contractors
Contractor Insurance Requirements: What Clients & GCs Actually Demand
How contractors can read client and GC insurance requirements, including limits, additional-insured status, waivers, primary/noncontributory terms, and certificates.
Carrier access
More insurance options. One agency in your corner.
With access to 100+ carrier markets, we do the shopping so you don’t have to contact each company yourself. Your Ellie agent helps you compare competitive quotes and choose insurance for the work you do.
+75 more
Next step
Compare workers' comp quotes for your business
Tell us about your payroll by job duty, ownership, locations, and recent loss runs, and an Ellie agent can shop options across carrier markets. Construction employers should also share subcontractor controls and project descriptions.