Skip to main content
Monday–Friday · 9:00 AM – 5:00 PM ET·independent · Insuring businesses nationwide
Trucking · Bobtail
Bobtail Insurance — liability when the tractor runs empty
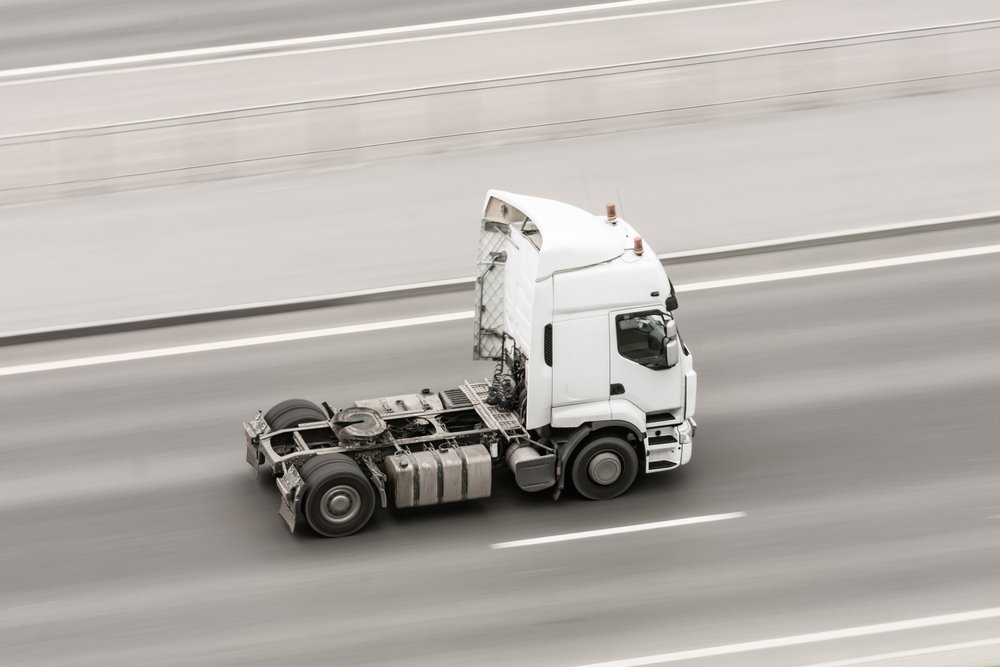
Bobtail insurance covers liability when an owner-operator drives the tractor without a trailer attached. It's typically purchased by drivers leased to a motor carrier to cover off-dispatch driving — running personal errands or between contracts. It is not the same as primary trucking liability or non-trucking liability, though the forms overlap.
At a Glance
- Coverage type
- Liability only
- Limit typical
- $1M CSL
- When
- No trailer attached
- Required by
- Most leasing carriers
Quick answer
Ellie Insurance Group is an independent business insurance agency headquartered in Tampa, Florida that shops 100+ carrier markets to review bobtail insurance needs for motor carriers and owner-operators. Commercial auto liability, physical damage, and motor truck cargo address different exposures; filings and federal financial responsibility depend on the operation and authority. A licensed agent can review your trucks, drivers, cargo, and lanes to discuss available options.
Coverage
What this trucking program covers
- Bodily injury liability
Injury to others when the tractor is bobtail.
- Property damage liability
Damage to others' property when bobtail.
- Defense costs
Legal defense for bobtail incidents.
Federal authority and the right insurance filings sit underneath all of this. If you run interstate, see how FMCSA filings and financial-responsibility rules (MCS-90, BMC-91/91X, BOC-3, and UCR) tie into the coverage above.
Common gaps
What it typically won't cover
- Any movement under dispatch (covered by the carrier's primary)
- Bobtail driven with a trailer attached (use NTL)
- Damage to the tractor itself (physical damage required separately)
- Cargo loss (motor truck cargo separately)
- Operations under the owner-operator's own authority
Illustrative loss scenarios
Where coverage questions arise
These examples illustrate exposures, not actual Ellie claims or guarantees of payment. The policy terms and loss facts determine whether a claim is covered.
Crash on the way to drop the trailer
A driver finishes a load and runs the tractor bobtail to the yard, then rear-ends a car at a light. With no trailer attached and no active dispatch, bobtail liability is the coverage that answers.
Fuel-stop parking-lot incident
While bobtail between assignments, the tractor backs into another vehicle at a truck stop. The carrier's primary liability doesn't apply off-dispatch, so the bobtail policy covers the third-party damage.
Mistaken reliance on the carrier policy
An owner-operator assumes the motor carrier insures every mile. After a bobtail wreck the carrier's insurer denies, leaving the driver personally liable — the exact gap bobtail coverage closes.
Pricing
What drives this premium
Tractor class
Class 8 OTR tractors rate higher than day cabs.
Driver MVRs
Clean MVRs keep bobtail in standard markets.
Leasing carrier
Some lessees require specific bobtail limits.
Operating radius
Long-haul rates slightly higher.
Loss history
Personal auto claims affect bobtail underwriting.
Coverage limit
Most bobtail policies are $1M CSL.
Want a realistic budget before you quote? See typical Florida truck insurance cost ranges by vehicle for primary liability, cargo, and full-program estimates across every equipment type.
Filings & compliance
Authority and insurance filings come first
Bobtail coverage is not an FMCSA filing; it backs up a leased owner-operator while the motor carrier's authority and MCS-90 cover dispatched miles. When a driver moves to their own authority, primary liability with BMC-91/91X filings replaces bobtail — we manage that transition.
Read the FMCSA filings guideQuote checklist
What we'll need to quote
Quote checklist
What we'll need to quote
- Tractor VIN and stated value
- Driver license and MVR
- Leasing carrier name and lease date
- Primary off-dispatch use
- Five-year loss history
- Current declarations pages
Related programs
Other trucking programs we write
Run a mixed fleet or a different unit? We place every major motor-carrier class across 100+ markets.
Semi-Truck
OTR and regional Class 8 tractor-trailer programs.
Learn more
Box Truck
Straight trucks for local delivery, moving, and last-mile freight.
Learn more
Dump Truck
Aggregate, debris, and construction hauling with on-site exposure.
Learn more
Flatbed
Open-deck freight with load-securement and tarping exposure.
Learn more
Hot Shot
Expedited loads on 1-ton duals and gooseneck trailers.
Learn more
See the full lineup on the trucking insurance hub.
FAQ
Frequently Asked Questions
- They're often used interchangeably, but technically bobtail means the tractor without a trailer, while NTL covers any off-dispatch operation. Many policies bundle both into one form.
- When the tractor is driven without a trailer — picking up a trailer, dropping one off, or running personal errands.
- No — owner-operators with their own authority need primary trucking liability instead. Bobtail is specifically for owner-operators leased to a motor carrier.
- The leasing carrier's primary liability covers you while under dispatch. Bobtail covers you when you're off-dispatch with no trailer attached.
Keep reading
Explore related coverage
Trucking Hub
All programs and core lines for motor carriers.
FMCSA Filings
MCS-90, BMC-91/91X, BOC-3, UCR, and authority explained.
Cost by Vehicle
Florida truck insurance price ranges by vehicle and operation.
Motor Truck Cargo
Cargo coverage by commodity.
Non-Trucking Liability
Liability questions for qualifying personal, nonbusiness use.
Commercial Auto
Auto liability fundamentals.
Workers' Compensation
WC for company drivers.
Sources
Authoritative references
- FMCSA — Insurance / Financial Responsibility Requirements
- III — Business Vehicle Insurance (Insuring Your Business)
- IRMI — Insurance Glossary
Coverage descriptions and regulatory figures on this page are general summaries reviewed against the references above and are not a statement of coverage, legal advice, or a guarantee of eligibility or price. Last reviewed . Requirements and policy terms change — always confirm current rules with the relevant agency and verify coverage against the actual policy and a licensed agent.
Carrier access
Access to 100+ A-rated commercial markets
As an independent agency we shop 100+ admitted and surplus-lines carrier markets — so the carrier competes for your business, not the other way around.
+75 more
Next step
Ready to shop commercial coverage?
Start an instant quote or speak with a commercial agent. We'll review available markets and the carrier's requirements before coverage can be bound.