Begin with the loss that could stop the job—not the trade label
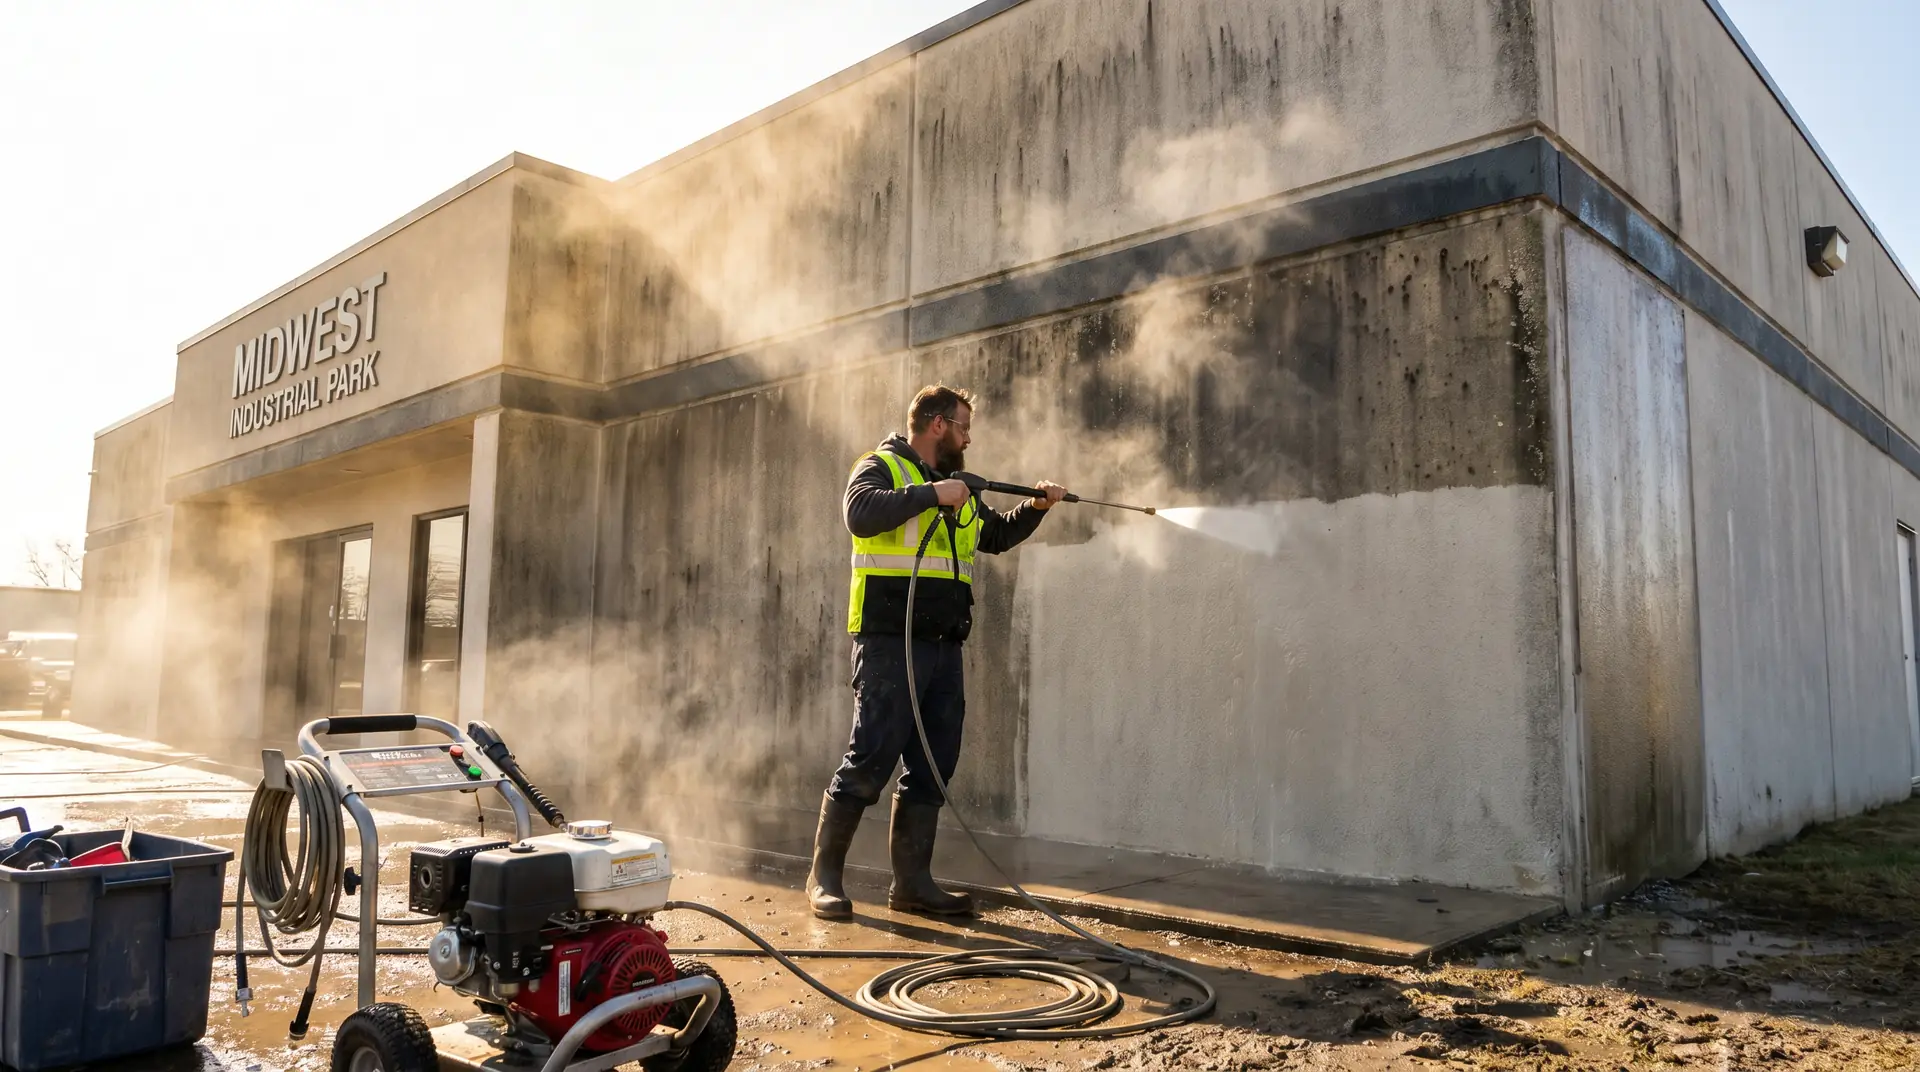
A driveway wash, roof soft wash, storefront cleaning, fleet wash, and multi-story exterior job may all be called pressure washing, but they put different property, people, vehicles, and chemicals at risk. Describe each service separately before choosing limits or comparing premiums. A short business description can leave out the one operation that changes the policy question: roof access, a lift, customer vehicles, or acid use.
Builders risk is not a substitute for liability arising from ordinary cleaning. It is property insurance generally intended for a covered construction or renovation project and its materials. Consider it only if a contract makes your business responsible for a qualifying project under construction; then compare the project property obligation with the separate liability exposure created by the cleaning work.
- Separate roof, height, soft-wash, high-pressure, flatwork, vehicle, and commercial-building work in the policy discussion.
- Identify every vehicle, trailer, pump, tank, and mobile or portable item the crew relies on, then ask which policy responds to road losses and which addresses the equipment itself.
- If the service mix changes during the policy term, ask what must be accepted or endorsed before the new operation begins.
Supporting references: Travelers — Builders Risk Insurance