Skip to main content
Monday–Friday · 9:00 AM – 5:00 PM ET·independent · Insuring businesses nationwide

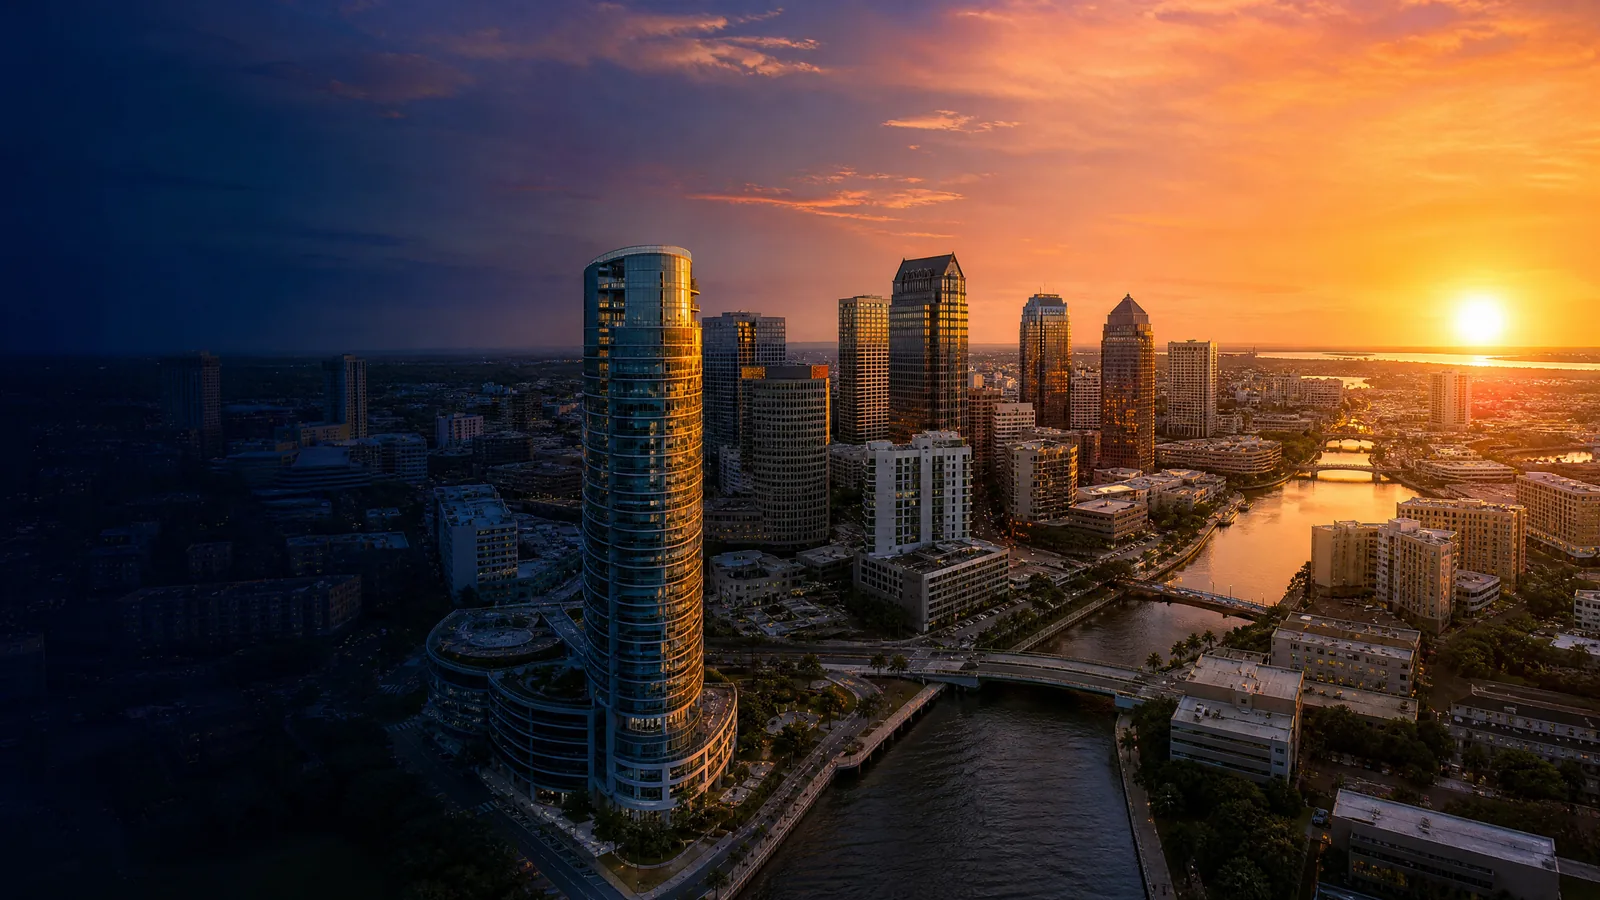
Tampa, FL · Trucking
Tampa trucking insurance for the work you do
Insurance for owner-operators and fleets hauling grain, general freight and local deliveries. Ellie helps Tampa business owners compare insurance and find competitive pricing. Tell us about your business—we’ll handle the shopping.
Trucking insurance for Tampa owner-operators and fleets. Whether you haul port freight, construction materials, or local deliveries, Ellie helps you compare trucking coverage and shop multiple insurance markets for competitive quotes. We’ll keep the next step simple for one truck or a growing fleet.
Ellie shops multiple insurance markets to help you compare coverage and competitive prices, with an agent guiding you from your first quote through ongoing service. Whether you run a single tractor-trailer under your own authority or manage a regional fleet with multiple drivers, compare primary auto liability, motor truck cargo, physical damage on tractors and trailers, and the MCS-90 endorsement and any required insurer filings. Non-trucking and bobtail coverage serve different purposes for owner-operators who lease to a carrier but also move equipment off-dispatch.
Your business and location
What to consider for trucking in Tampa
Tampa Bay's underwriting environment adds layers that carriers in less-exposed markets rarely price into a base policy. Wind and hurricane exposure affects physical damage rates on equipment stored or garaged in coastal Hillsborough County. Port Tampa Bay access and individual terminal, carrier, broker, or shipper contracts can impose different credential, insurance, cargo-limit, and indemnity requirements. Get the applicable agreement before binding coverage. For port-licensed for-hire transport businesses subject to the Motor Carrier Act, the Port tariff calls for evidence of an MCS-90 endorsement on business auto liability. Flood mapping is relevant for yards and terminals situated near Tampa's low-lying corridors. Florida's active claims and litigation environment also influences liability appetite — radius of operation, commodity type, and clean driver MVRs carry significant weight with underwriters working this market.
Illustrative scenario
Port Run to Plant City: When One Policy Gap Creates Two Problems
A Tampa-based owner-operator picks up a refrigerated load at a Port of Tampa terminal and delivers to a distribution warehouse near Plant City. En route on I-4, a sudden hard stop causes cargo shift and product damage. Without a motor truck cargo policy written to cover temperature-sensitive freight, the driver absorbs the shipper's claim personally. Before accepting a load, match the coverage to the trip. Confirm who provides primary liability while you are dispatched; whether you have physical-damage coverage for the tractor and trailer; whether your cargo limit, deductible, listed commodities, and refrigeration-breakdown protection fit the load; and whether a trailer-interchange, bobtail, or non-trucking-liability requirement appears in your lease. Non-trucking liability typically addresses personal use, not dispatched work, cargo loss, or damage to your own truck. Two separate coverage gaps, both avoidable with a properly structured trucking program.
Example for illustration only. Coverage depends on your policy's terms, limits, and exclusions.
Trucking coverage
Coverages Tampa trucking typically buy
- Primary Auto Liability
Required truck-liability limits and filings can come from federal or Florida rules, operating authority, cargo, or a contract. An MCS-90, when required, supports public-liability obligations; it does not insure freight or truck damage.
- Motor Truck Cargo
Protects the freight you haul against loss or damage.
- Physical Damage
Collision and comprehensive on tractors and trailers.
- Non-Trucking / Bobtail
Non-trucking liability addresses qualifying nonbusiness use. Bobtail policy definitions vary; being off dispatch or without a trailer is not enough to determine coverage.
Tampa considerations
Local factors for trucking in Tampa
- Hurricane / wind
Wind eligibility drives Tampa Bay property pricing; coastal exposures may require separate wind deductibles and specialty markets.
- Port and logistics
Port and distribution activity can create vehicle, cargo, and equipment-in-transit exposures. Cargo coverage and an MCS-90 apply only to operations that trigger those separate requirements.
- Flood mapping
Flood is generally insured separately from commercial property. A lender may require flood insurance when a property is in a high-risk area and has a government-backed mortgage.
- AOB and litigation
Florida's claims environment is among the most active in the country; appetite and pricing reflect this.
Tampa · Trucking
Trucking coverage built for Tampa businesses
You run your business; we shop the insurance. Compare competitive quotes with an Ellie agent who helps you understand your coverage and supports you after you buy.
More Tampa industries
Other classes we insure in Tampa
Tampa Contractors
Insurance for general contractors and specialty trades—from your jobsite work to your crews, tools and work vehicles.
Learn more
Tampa Restaurants
Insurance for restaurants, bars, breweries and caterers—from your dining room and kitchen to your staff and deliveries.
Learn more
Tampa Real Estate Investors
Insurance for rental properties, renovation projects and growing investment portfolios.
Learn more
Verified Google Reviews
5.0★ on Google · read every review at the source
Google supplies the rating and selected review content when available. Visit Google to see the current rating and all reviews.
5.0★ on Google
Read every verified review directly on Google — we don't post curated testimonials on this site.
FAQ
Frequently Asked Questions
- Yes. Port of Tampa operations typically trigger requirements for motor truck cargo forms that address terminal liability and inland marine exposures that a standard cargo endorsement may not cover. Some terminal operators and shippers also require minimum cargo limits and specific policy language before a driver can load. If your routes run from the port into Florida's interstate corridors, carriers will also want to confirm your MCS-90 endorsement is current and that your primary auto liability limits meet FMCSA minimums for the commodities you haul.
- Not always, but the core requirements are similar. Start with your authority, whether you haul for hire, vehicle weight, and cargo. Required auto-liability limits and filings can apply; cargo insurance is federally required for household-goods carriers, while other cargo limits are commonly contractual. Physical-damage coverage is a business decision to protect a financed, leased, or owned truck and trailer. Compare the cargo limit, deductible, commodity restrictions, and any temperature-control endorsement with your load contracts. Because hot-shot operations in the Brandon and Riverview corridor often haul for contractors and light-industrial accounts, commodity type matters — tools, equipment, and building materials may require different cargo sublimits than a refrigerated or oversized load program would carry.
- Florida's litigation climate is among the most active in the country, and Hillsborough County is a densely trafficked commercial market. Underwriters price auto liability for trucks operating on I-4, I-75, and local Tampa corridors with that exposure in mind. Pricing and availability vary by insurer and depend on the operation, vehicles, drivers and driving history, garaging location, radius, cargo, claims, and safety controls. Ask which of those factors is affecting your terms and whether a change in deductible, cargo limit, or coverage structure changes the quote. Maintaining clean driver records and working with an independent agency that shops multiple markets helps identify the most competitive options available for your specific operation.
- Owner-operators, fleets, hot-shot haulers, and distribution operations running through Florida's ports and interstate corridors. A typical Tampa program combines several of these coverages based on the operation, contracts, and exposures.
- Cost depends on the size of the operation, payroll or revenue, vehicles, prior claims, and Florida-specific factors. Florida's ports and I-4/I-75/I-95 corridors drive heavy logistics demand. Radius of operation, commodity hauled, and driver MVRs are the biggest pricing levers. An Instant Quote across 100+ markets is the most accurate way to know.
- Florida's ports and I-4/I-75/I-95 corridors drive heavy logistics demand. Radius of operation, commodity hauled, and driver MVRs are the biggest pricing levers.
- Yes. As an independent agency we shop 100+ carrier markets for trucking insurance, including specialty markets for harder-to-place trucking. Tampa is part of our core Florida service area.
Keep reading
Explore related coverage
Tampa Commercial Insurance
Explore insurance options for your Tampa business.
Florida Commercial Insurance
Statewide Florida commercial markets.
Instant Quote
Start an Instant Quote for a Tampa business.
Trucking (Industry Hub)
How we insure trucking statewide.
Tampa Contractors
Insurance for general contractors and specialty trades—from your jobsite work to your crews, tools and work vehicles.
Tampa Restaurants
Insurance for restaurants, bars, breweries and caterers—from your dining room and kitchen to your staff and deliveries.
Carrier access
More insurance options. One agency in your corner.
With access to 100+ carrier markets, we do the shopping so you don’t have to contact each company yourself. Your Ellie agent helps you compare competitive quotes and choose insurance for the work you do.
+75 more
Next step
Let's find insurance for your business
Tell us about your business. We’ll shop our insurance markets for competitive quotes and help you compare coverage, price and the support you need from your agency.