Skip to main content
Monday–Friday · 9:00 AM – 5:00 PM ET·independent · Insuring businesses nationwide

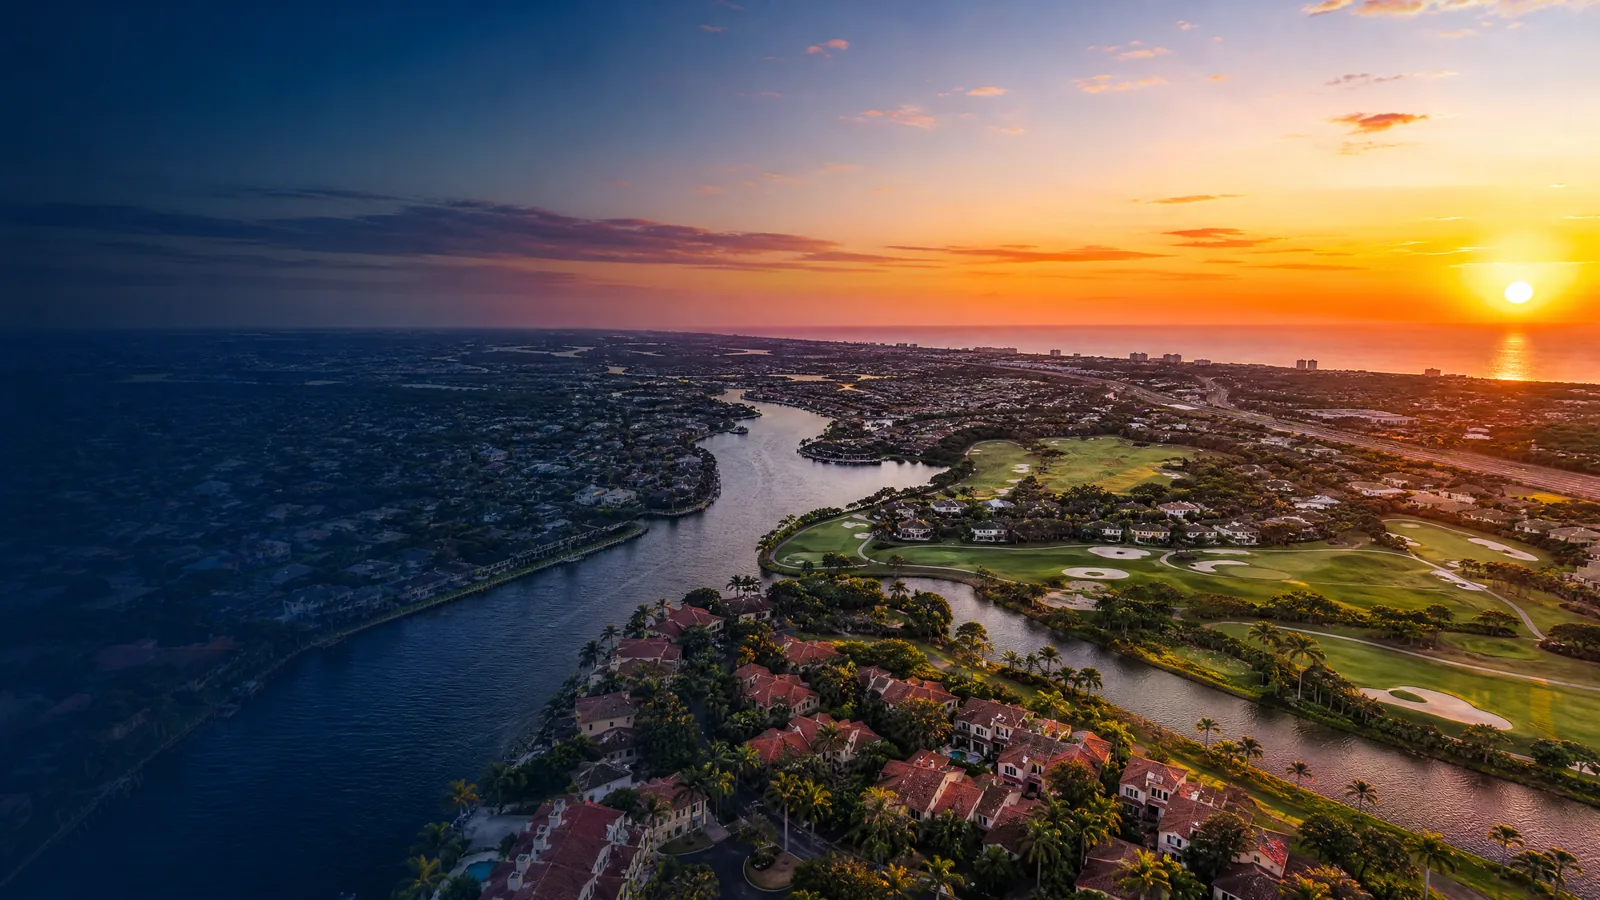
Port St. Lucie, FL · Retail
Port St. Lucie retail insurance for the work you do
Insurance for storefronts and specialty retailers, with options for your customers, stock, shop and employees. Ellie helps Port St. Lucie business owners compare insurance and find competitive pricing. Tell us about your business—we’ll handle the shopping.
Census estimates put Port St. Lucie's population at 268,062 on July 1, 2025, up 30.9% from the April 2020 estimate. Growth does not change what your policy covers, so base coverage decisions on your lease, property, stock, and operations. Shopping plazas in St. Lucie West draw steady foot traffic from established neighborhoods, while Tradition's master-planned commercial district continues to attract specialty shops, healthcare-adjacent retail, and service-oriented storefronts. That growth creates real opportunity — and real exposure. For an eligible retail business, a BOP can combine general liability and commercial property. If a BOP does not fit, those coverages may be bought separately. Crime coverage is optional and should be chosen for the risks your store actually carries.
Availability and terms depend on the carrier, address, store operations, prior losses, and policy requirements. Ask which options are currently available for your operation and which terms differ before choosing coverage. Whether you run a boutique in Tradition, a convenience store along the US-1 corridor, or a specialty shop near Becker Road, your coverage needs are shaped by Florida's hurricane wind environment, local theft patterns, and the liability limits your commercial lease likely requires. Kevin Smith and the Ellie team will walk you through your options and help you compare quotes without pressure or guesswork.
Your business and location
What to consider for retail in Port St. Lucie
St. Lucie County sits squarely in the Treasure Coast's Atlantic wind corridor, meaning retail property policies must be evaluated for wind eligibility, hurricane deductibles, and coverage on inventory and tenant improvements — not just the building shell. Standard commercial property/BOP coverage generally does not cover flood. If you want flood protection, compare a separate commercial flood policy; a lender or lease may separately require it. Check the property's FEMA map and the policy's building, contents, and business-income limits. In high-traffic plazas like St. Lucie West, slip-and-fall liability and product claims are routine underwriting considerations, and carriers will review your store's security measures when pricing crime coverage.
Illustrative scenario
When a Storm Shuts Down a St. Lucie West Storefront
A specialty retailer leasing space in a St. Lucie West shopping plaza sustains wind-driven roof damage during a named storm. Without clearly structured commercial property coverage that addresses hurricane deductibles and tenant improvements, the business faces repair costs it cannot recover through the landlord's building policy alone. Inventory losses compound the setback. After a covered direct physical loss, the policy may cover insured stock or tenant improvements and may provide business-income coverage. Check the declarations and policy for the cause of loss, wind deductible, covered-property limit, valuation, business-income waiting period, period of restoration, exclusions, and what the lease makes the tenant responsible for.
Example for illustration only. Coverage depends on your policy's terms, limits, and exclusions.
Retail coverage
Coverages Port St. Lucie retail typically buy
- Business Owners Policy
Bundles liability and property for eligible retail risks.
- General Liability
Customer injury and product liability.
- Commercial Property
Inventory, fixtures, and tenant improvements.
- Crime / Theft
Employee dishonesty and money-and-securities coverage.
Port St. Lucie considerations
Local factors for retail in Port St. Lucie
- Construction and service work
Match coverage to actual job duties, payroll, and subcontracted work.
- Atlantic wind
Treasure Coast wind exposure can affect property terms and deductibles.
- Flood exposure
Canal-front and coastal properties may need separate flood coverage; check the address, financing, and policy.
- Residential services
Residential construction and service work can create liability, vehicle, employee, and equipment exposures.
- I-95 corridor
I-95 supports freight movement; motor carriers should confirm the coverage and filing requirements for their operations.
Port St. Lucie · Retail
Retail coverage built for Port St. Lucie businesses
You run your business; we shop the insurance. Compare competitive quotes with an Ellie agent who helps you understand your coverage and supports you after you buy.
More Port St. Lucie industries
Other classes we insure in Port St. Lucie
Port St. Lucie Contractors
Insurance for general contractors and specialty trades—from your jobsite work to your crews, tools and work vehicles.
Learn more
Port St. Lucie Real Estate Investors
Insurance for rental properties, renovation projects and growing investment portfolios.
Learn more
Port St. Lucie Restaurants
Insurance for restaurants, bars, breweries and caterers—from your dining room and kitchen to your staff and deliveries.
Learn more
Verified Google Reviews
5.0★ on Google · read every review at the source
Google supplies the rating and selected review content when available. Visit Google to see the current rating and all reviews.
5.0★ on Google
Read every verified review directly on Google — we don't post curated testimonials on this site.
FAQ
Frequently Asked Questions
- In most cases, yes. Your lease—not Florida insurance law—sets the limits and endorsements you promise the landlord. Before signing, compare its insurance and indemnity clauses with the policy: required liability limits, additional-insured wording, who insures the building versus improvements and stock, waiver requirements, and certificate timing. Confirm that the carrier can issue the requested endorsement. Before you finalize a lease or renew an existing one, reviewing those requirements with a licensed agent helps ensure your policy meets the contract terms and protects you from a default clause triggered by inadequate coverage.
- Not always. Florida retail underwriting, particularly on the Treasure Coast where Atlantic wind exposure is elevated, often involves separate wind deductibles or, in some cases, wind exclusions that push coverage to the Florida market. Retailers in Port St. Lucie should confirm whether their BOP covers wind damage to inventory and tenant improvements, and at what deductible threshold. Ellie shops multiple carrier markets to find policies where wind eligibility and deductible structure work for your specific St. Lucie County location.
- Crime coverage is optional and should be read by insuring agreement. Confirm whether it includes employee theft, money and securities, forgery or alteration, and any funds-transfer, computer-fraud, or social-engineering protection you need. Do not assume it covers shoplifting, inventory shortages, chargebacks, or cyber fraud; verify the policy, limit, and deductible that apply. For storefronts along the US-1 corridor or convenience-oriented locations in Port St. Lucie, carriers will often look at your cash-handling procedures, safe equipment, and security systems when pricing this coverage. Employee dishonesty is a frequently overlooked exposure — a trusted staff member causing a loss is not covered under general liability, making a standalone crime endorsement or floater an important addition to a complete retail program.
- Boutiques, specialty shops, convenience stores, and big-box retail across Florida's shopping districts and plazas. A typical Port St. Lucie program combines several of these coverages based on the operation, contracts, and exposures.
- Cost depends on the size of the operation, payroll or revenue, vehicles, prior claims, and Florida-specific factors. Wind and flood are different risks. Ask whether the property policy excludes flood and whether separate flood coverage is needed for inventory, equipment, and tenant improvements; theft exposure can also vary by location. Leases usually dictate the required liability limits. An Instant Quote across 100+ markets is the most accurate way to know.
- Wind and flood are different risks. Ask whether the property policy excludes flood and whether separate flood coverage is needed for inventory, equipment, and tenant improvements; theft exposure can also vary by location. Leases usually dictate the required liability limits.
- Yes. As an independent agency we shop 100+ carrier markets for retail business insurance, including specialty markets for harder-to-place retail. Port St. Lucie is part of our core Florida service area.
Keep reading
Explore related coverage
Port St. Lucie Commercial Insurance
Explore insurance options for your Port St. Lucie business.
Florida Commercial Insurance
Statewide Florida commercial markets.
Instant Quote
Start an Instant Quote for a Port St. Lucie business.
Retail (Industry Hub)
How we insure retail statewide.
Port St. Lucie Contractors
Insurance for general contractors and specialty trades—from your jobsite work to your crews, tools and work vehicles.
Port St. Lucie Real Estate Investors
Insurance for rental properties, renovation projects and growing investment portfolios.
Carrier access
More insurance options. One agency in your corner.
With access to 100+ carrier markets, we do the shopping so you don’t have to contact each company yourself. Your Ellie agent helps you compare competitive quotes and choose insurance for the work you do.
+75 more
Next step
Let's find insurance for your business
Tell us about your business. We’ll shop our insurance markets for competitive quotes and help you compare coverage, price and the support you need from your agency.