Skip to main content
Monday–Friday · 9:00 AM – 5:00 PM ET·independent · Insuring businesses nationwide
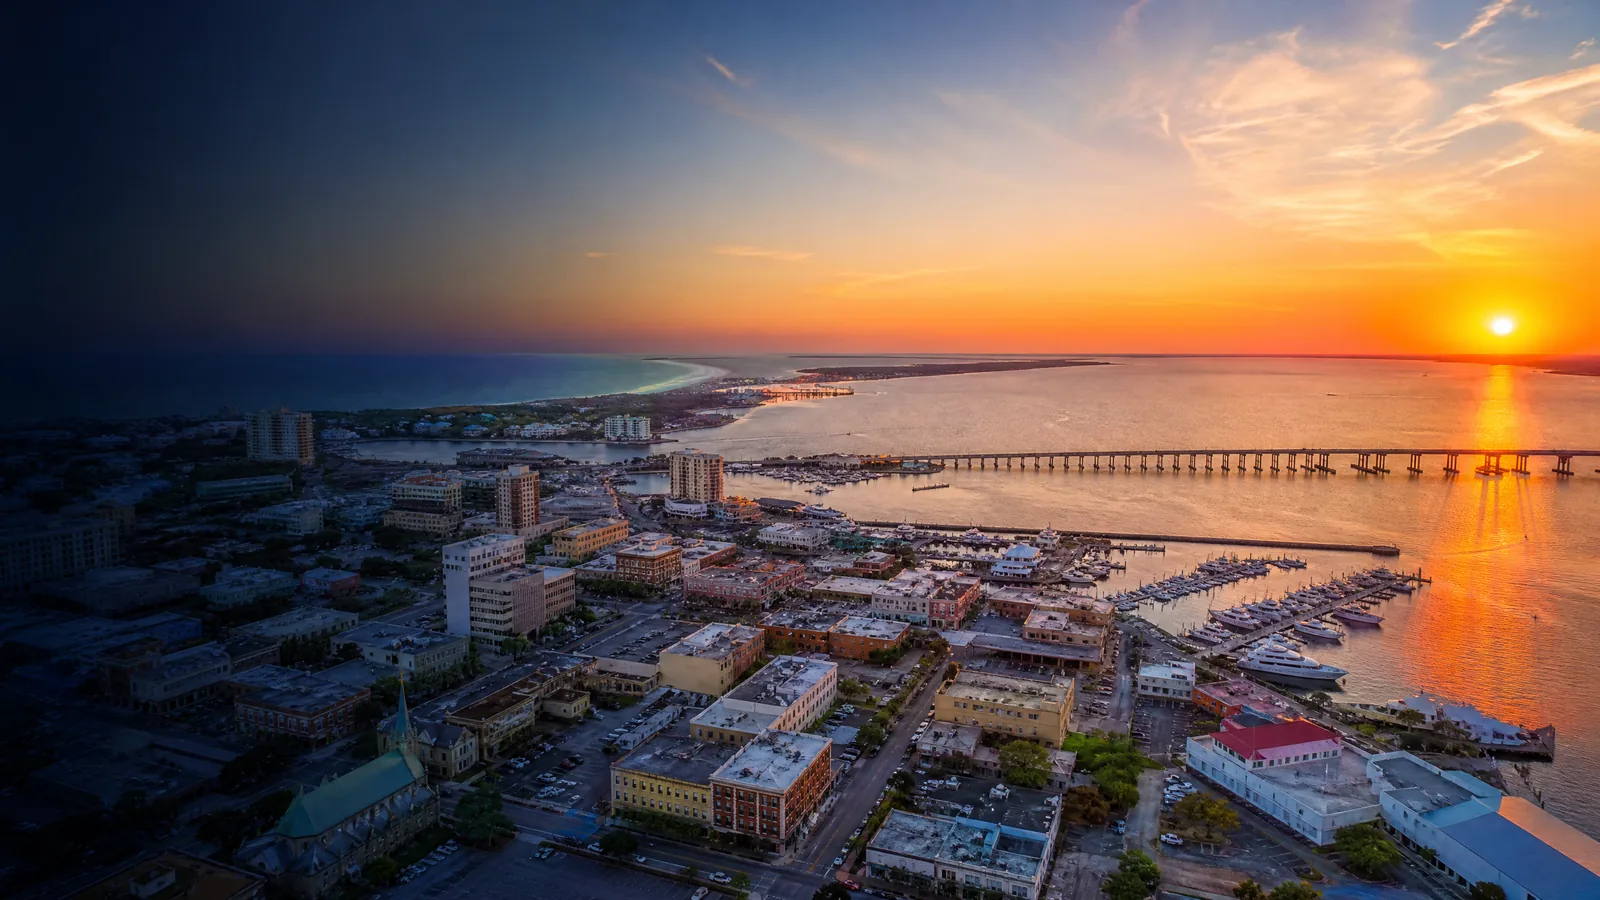
Pensacola, FL · Business Owners Policy (BOP)
Pensacola business owners policy (bop) insurance for local businesses
Bring business liability and property insurance together in a package that is easier to manage. Ellie helps Pensacola businesses compare insurance options and find competitive pricing—with one agent handling the shopping.
Business owners policy insurance for Pensacola shops, restaurants, offices, and service businesses. A BOP can combine property and liability coverage for eligible operations; Ellie helps you compare the package and shop multiple insurance markets for competitive quotes. Keep your next step simple while you focus on serving Gulf Coast customers.
Carrier availability for a Pensacola BOP depends on the address, construction, roof, operations, loss history, and the insurer’s current appetite. Ask which available options cover wind, what deductible applies, and whether the insurer is admitted or surplus lines. Wind eligibility, named-storm deductibles, and proximity to Escambia Bay or the Gulf can shift a business from one carrier's appetite to another's. Kevin Smith and the Ellie team evaluate your specific address, building age, and operations to find a BOP that fits — or, when BOP eligibility is restricted near the coast or for older structures, they package monoline general liability and commercial property to reach comparable coverage. If a BOP is not available, separate property and liability policies may be an option. Compare the limits, deductibles, endorsements, exclusions, and policy periods together to identify whether important exposures remain uninsured.
Your business and location
What to consider for business owners policy (bop) in Pensacola
Pensacola's Gulf and Escambia Bay exposure drives the most important underwriting questions on any BOP request. Carriers scrutinize wind-resistance ratings, roof age, and construction type before quoting, and Your declarations may show a separate wind, hurricane, or named-storm deductible. It can be a dollar amount or a percentage, so calculate the dollar amount and confirm when it applies before choosing the policy. Flood is ordinarily excluded under a standard BOP, so ask whether separate flood coverage is appropriate for your location, property interest, lender requirements, and loss tolerance. Compare building and contents limits separately. If you use NFIP coverage, remember it generally does not cover business interruption or loss of use, and a new policy commonly has a 30-day waiting period unless an exception applies.
Illustrative scenario
A Palafox Street Retail Shop Weathers a Wind-Damage Claim
A retail shop occupying a street-level space in Pensacola's downtown Palafox corridor takes roof damage during a named storm, forcing a two-week closure for repairs. After wind damage, check the declarations page: confirm wind coverage, the storm or wind deductible, the building and business-personal-property limits, and who owns the damaged improvements. Business-income coverage generally applies only when a covered physical loss causes a suspension, and it runs only for the policy’s restoration period. A government closure, contractor delay, or lost sales alone may not trigger it. General liability is a separate coverage part and responds only to covered claims under its terms.
Example for illustration only. Coverage depends on your policy's terms, limits, and exclusions.
Business Owners Policy (BOP) coverage
What business owners policy (BOP) covers in Pensacola
- General liability (bodily injury and property damage)
- Commercial property (building and contents)
- Business income after a covered property loss, subject to the waiting period and period of restoration
- May be available by endorsement or separate policy: equipment breakdown; cyber or data coverage; and hired and non-owned auto liability
- Simplified billing and one renewal
Pensacola considerations
Local factors that affect your business owners policy (bop) program
- Gulf wind
Panhandle Gulf exposure makes wind eligibility and deductibles critical.
- Flood zones
Flood damage is typically addressed by a separate NFIP or private flood policy. Confirm lender and lease requirements, building and contents limits, deductibles, and whether business-income loss is covered.
- Marine
Waterfront, marina, and marine-service operations need specialized coverage.
- Construction
Steady construction and remodeling drives GL and builder's-risk demand.
Pensacola · Business Owners Policy (BOP)
An Ellie agent in your corner
Get help comparing business owners policy (BOP) for your Pensacola business. We shop multiple markets for competitive quotes and explain your choices in plain language.
More Pensacola coverage
Other commercial policies for Pensacola businesses
Pensacola General Liability
Help protect your business when a customer is injured or your work damages someone else’s property.
Learn more
Pensacola Workers' Compensation
Help employees recover from work injuries and protect your business with workers’ compensation insurance.
Learn more
Pensacola Commercial Auto
Insurance for work trucks, service vans and fleets—built around the driving your business does.
Learn more
Verified Google Reviews
5.0★ on Google · read every review at the source
Google supplies the rating and selected review content when available. Visit Google to see the current rating and all reviews.
5.0★ on Google
Read every verified review directly on Google — we don't post curated testimonials on this site.
FAQ
Frequently Asked Questions
- BOP property coverage generally includes wind, but Panhandle coastal locations in Escambia County often trigger named-storm deductibles expressed as a percentage of the insured building value rather than a flat dollar figure. Some carriers restrict BOP eligibility entirely for properties within a certain distance of the Gulf or bay, which is why Ellie shops multiple markets and, when needed, moves to monoline property placement that still achieves comparable protection.
- No. Flood is excluded from standard BOP property coverage regardless of insurer. Pensacola Beach and other low-lying coastal and bayfront areas of Escambia County carry significant flood exposure, and a separate flood policy — typically through the National Flood Insurance Program or a private flood carrier — is necessary to cover that gap. Ellie evaluates your flood zone designation and helps place the appropriate companion coverage alongside your BOP or monoline property policy.
- Many small contractors in Pace and Milton in Santa Rosa County may qualify for a BOP, depending on the trade, premises, payroll, revenue, and carrier eligibility., which can cover a business office, tools and equipment stored there, and general liability in one policy. However, A BOP may fit a contractor’s office or shop, but it is not a complete jobsite program. Confirm how tools away from the premises, materials on an active project, vehicles, employees, and contract-required additional-insured coverage are handled. Those needs may require endorsements or separate inland marine, builders-risk, auto, workers’ compensation, or other policies. Kevin Smith can assess your specific operations to confirm whether a BOP covers your core exposure or whether a broader commercial package is more appropriate.
- Bring business liability and property insurance together in a package that is easier to manage. For Pensacola businesses, the exact coverage depends on the policy form, limits, deductibles, endorsements, and exclusions selected.
- Eligible small to mid-sized Florida businesses — retail, offices, restaurants, and service firms — that want liability and property bundled at a lower combined premium.
- Business Owners Policy (BOP) pricing in Pensacola reflects the business class, size, payroll or sales, prior claims, and Florida-specific factors. Coastal location, construction, roof condition, prior losses, occupancy, and the property address can affect whether an insurer offers a BOP and what wind terms or deductibles apply. Separate liability and property policies can address core exposures, but compare their limits, deductibles, business-income terms, and endorsements rather than assuming the protection is the same. The most accurate way to know your cost is an Instant Quote across 100+ carrier markets.
- Coastal location, construction, roof condition, prior losses, occupancy, and the property address can affect whether an insurer offers a BOP and what wind terms or deductibles apply. Separate liability and property policies can address core exposures, but compare their limits, deductibles, business-income terms, and endorsements rather than assuming the protection is the same.
- Yes. As an independent agency we shop 100+ carrier markets for business owners policy (BOP), including admitted and specialty markets when an account does not fit a single carrier's appetite. Pensacola is part of our core Florida service area.
Keep reading
Explore related coverage
Pensacola Commercial Insurance
Explore insurance options for your Pensacola business.
Florida Commercial Insurance
Statewide Florida commercial markets.
Instant Quote
Start an Instant Quote for a Pensacola business.
Business Owners Policy (BOP) (Coverage Hub)
How business owners policy (BOP) works and what it covers.
Pensacola General Liability
Help protect your business when a customer is injured or your work damages someone else’s property.
Pensacola Workers' Compensation
Help employees recover from work injuries and protect your business with workers’ compensation insurance.
Carrier access
More insurance options. One agency in your corner.
With access to 100+ carrier markets, we do the shopping so you don’t have to contact each company yourself. Your Ellie agent helps you compare competitive quotes and choose insurance for the work you do.
+75 more
Next step
Let's find insurance for your business
Tell us about your business. We’ll shop our insurance markets for competitive quotes and help you compare coverage, price and the support you need from your agency.