Skip to main content
Monday–Friday · 9:00 AM – 5:00 PM ET·independent · Insuring businesses nationwide
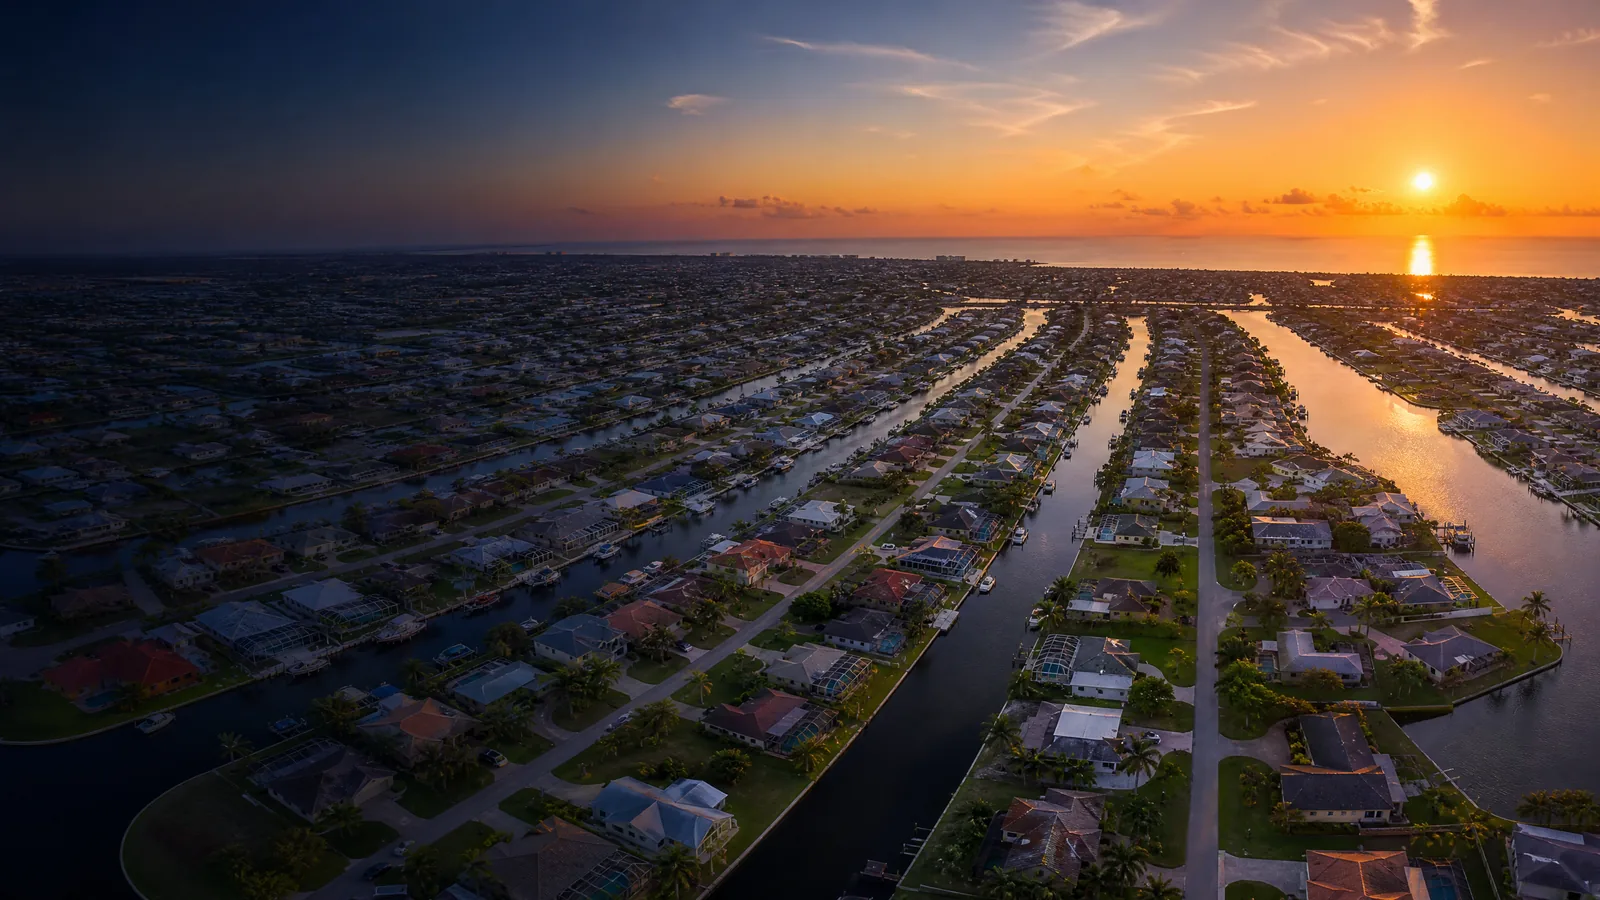
Cape Coral, FL · Real Estate Investors
Cape Coral real estate investors insurance for the work you do
Insurance for rental properties, renovation projects and growing investment portfolios. Ellie helps Cape Coral business owners compare insurance and find competitive pricing. Tell us about your business—we’ll handle the shopping.
Real estate investor insurance for Cape Coral landlords and property owners. Whether you manage rentals, renovate a flip, or prepare a canal-front property for tenants, Ellie helps you compare coverage and shop multiple insurance markets for competitive quotes. Choose a policy that fits how you own and use each address.
Real estate investor insurance in Cape Coral must account for the city's layered risk environment: active hurricane zones, widespread FEMA flood designations, aging roof stock, and a large inventory of properties cycling between tenants, renovation crews, and short-term guests. A landlord policy addresses liability and physical damage for occupied rentals, while vacant-property and builder's risk forms close the coverage gaps during turnovers and gut rehabs. Short-term rental owners along the waterfront submarkets need specialty markets that most regional carriers decline to write. Ellie's independent model means your portfolio gets placed with carriers whose appetite matches Cape Coral's specific exposure profile.
Your business and location
What to consider for real estate investors in Cape Coral
Cape Coral's underwriting environment is among the most demanding in Southwest Florida. Flood damage is usually not included in a landlord or dwelling policy. Check the address in Cape Coral’s flood portal and review the loan requirements. Flood insurance is required when a property in a high-risk area has a mortgage from a government-backed lender; otherwise it can still be an important optional protection. NFIP and private policies differ in limits, waiting periods, and covered property. Review the declarations page for the actual dollar wind or hurricane deductible and whether it applies per hurricane or annually. Older roofs can affect eligibility, valuation, and price, but a surplus-lines policy is not automatic. If one is offered, compare its coverage and deductible carefully; surplus-lines policyholders are not protected by FIGA. Vacant lots with active seawalls and dock structures add marine liability that standard landlord forms do not cover.
Illustrative scenario
Canal-Front Fix-and-Flip: Covering the Gaps Between Purchase and Resale
An investor acquires a canal-front property in South Cape following hurricane damage, intending to complete a full renovation and list it within several months. Vacancy and renovation can change coverage before a loss occurs. Ask for the written vacancy condition and confirm whether wind, water, theft or vandalism, liability, existing structure, materials, and loss of rents are covered. A project policy and the completed-property policy are separate coverage decisions; arrange the next policy or endorsement before occupancy changes. Throughout both phases, a separate flood policy remains in force because the parcel sits in a designated flood zone regardless of occupancy status.
Example for illustration only. Coverage depends on your policy's terms, limits, and exclusions.
Real Estate Investors coverage
Coverages Cape Coral real estate investors typically buy
- Landlord / Dwelling
Rental property liability and physical damage.
- Vacant Property
Coverage for unoccupied or between-tenant buildings.
- Builder's Risk
Renovation and ground-up construction projects.
- General Liability
Premises liability across a portfolio.
Cape Coral considerations
Local factors for real estate investors in Cape Coral
- Canal / marine
Extensive canals create dock, seawall, and marine exposure.
- Hurricane rebuilding
Heavy post-storm construction drives contractor coverage demand.
- Flood zones
Cape Coral has mapped flood exposure. Check the building address and loan or lease; standard commercial property typically excludes flood, so separate coverage may be needed for the building, contents, or both.
- Gulf wind
Strict wind underwriting and deductibles for coastal property.
Cape Coral · Real Estate Investors
Real Estate Investors coverage built for Cape Coral businesses
You run your business; we shop the insurance. Compare competitive quotes with an Ellie agent who helps you understand your coverage and supports you after you buy.
More Cape Coral industries
Other classes we insure in Cape Coral
Verified Google Reviews
5.0★ on Google · read every review at the source
Google supplies the rating and selected review content when available. Visit Google to see the current rating and all reviews.
5.0★ on Google
Read every verified review directly on Google — we don't post curated testimonials on this site.
FAQ
Frequently Asked Questions
- In most cases, yes. The majority of Cape Coral sits within FEMA-designated flood zones, and standard landlord or dwelling-fire policies do not cover flood damage regardless of cause. Flood coverage must be purchased separately, either through the National Flood Insurance Program or a private flood carrier. For investors holding multiple properties across Lee County, Ellie can review each parcel's flood zone designation and identify whether private flood markets offer better terms than the federal program for your specific addresses.
- Disclose short-term-rental use before binding. Ask whether the policy permits the planned rental frequency and covers guest liability, furnished contents, loss of rents after a covered loss, and any dock, seawall, lift, or watercraft exposure. Availability and limits vary by carrier and address. Separately, confirm Cape Coral rental registration and the City/DBPR operating requirements before accepting guests. Ellie works with specialty and surplus-lines carriers that specifically write short-term rental programs in Southwest Florida, covering liability, physical damage, and loss-of-rental-income for platforms such as those common in Cape Coral's waterfront tourism market.
- Most landlord and dwelling-fire policies contain a vacancy clause that suspends or voids certain coverages — including vandalism, water damage, and sometimes wind — after a property has been unoccupied for 30 to 60 consecutive days. North Cape's active contractor and residential-services market means turnovers involving renovation work can easily exceed that threshold. Ellie can place a vacant-property or builder's risk endorsement to maintain continuous coverage through the gap period, preventing the uninsured exposure that often catches investors off guard between Lee County tenancies.
- Buy-and-hold landlords, fix-and-flip investors, short-term rental owners, and portfolio holders across Florida. A typical Cape Coral program combines several of these coverages based on the operation, contracts, and exposures.
- Cost depends on the size of the operation, payroll or revenue, vehicles, prior claims, and Florida-specific factors. Florida's wind, flood, and roof-age rules heavily affect investor property pricing. Short-term rentals and vacant properties need specialty markets most standard carriers won't write. An Instant Quote across 100+ markets is the most accurate way to know.
- Florida's wind, flood, and roof-age rules heavily affect investor property pricing. Short-term rentals and vacant properties need specialty markets most standard carriers won't write.
- Yes. As an independent agency we shop 100+ carrier markets for real estate investor insurance, including specialty markets for harder-to-place real estate investors. Cape Coral is part of our core Florida service area.
Keep reading
Explore related coverage
Cape Coral Commercial Insurance
Explore insurance options for your Cape Coral business.
Florida Commercial Insurance
Statewide Florida commercial markets.
Instant Quote
Start an Instant Quote for a Cape Coral business.
Real Estate Investors (Industry Hub)
How we insure real estate investors statewide.
Cape Coral Contractors
Insurance for general contractors and specialty trades—from your jobsite work to your crews, tools and work vehicles.
Cape Coral Retail
Insurance for storefronts and specialty retailers, with options for your customers, stock, shop and employees.
Carrier access
More insurance options. One agency in your corner.
With access to 100+ carrier markets, we do the shopping so you don’t have to contact each company yourself. Your Ellie agent helps you compare competitive quotes and choose insurance for the work you do.
+75 more
Next step
Let's find insurance for your business
Tell us about your business. We’ll shop our insurance markets for competitive quotes and help you compare coverage, price and the support you need from your agency.