Skip to main content
Monday–Friday · 9:00 AM – 5:00 PM ET·independent · Insuring businesses nationwide

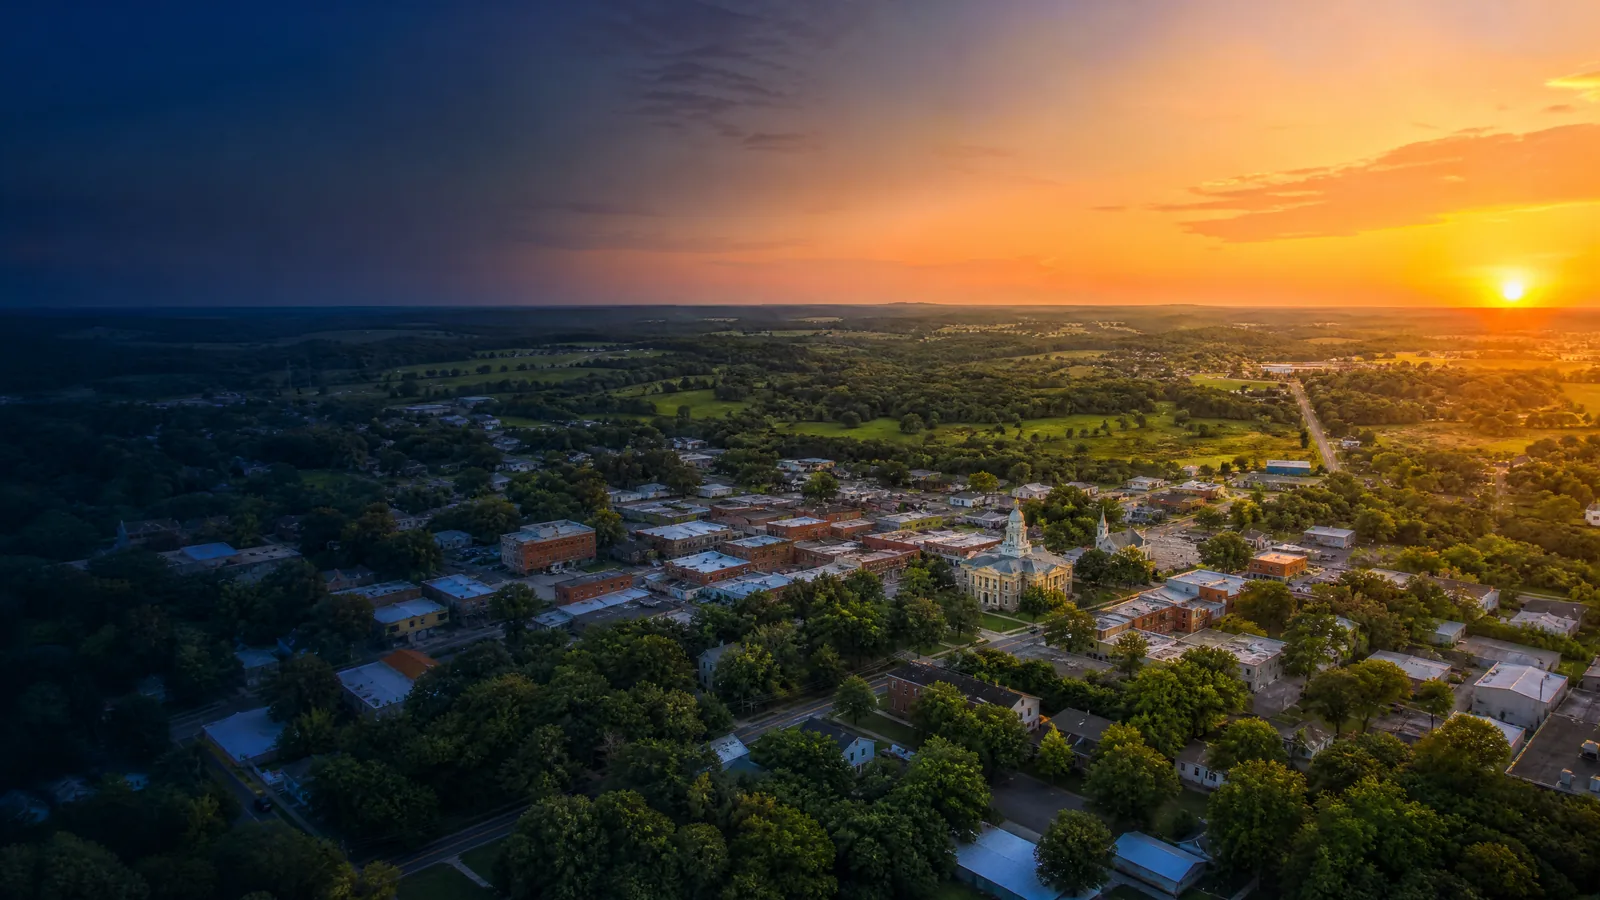
Brooksville, FL · Commercial Property
Brooksville commercial property insurance for local businesses
Compare insurance for the building, inventory and equipment your business relies on every day. Ellie helps Brooksville businesses compare insurance options and find competitive pricing—with one agent handling the shopping.
Brooksville and Hernando County businesses face a property insurance landscape shaped by the Nature Coast's unique mix of industries and exposures. Whether you operate a retail shop on a Downtown Brooksville side street, run a hospitality venue near Weeki Wachee, or manage a contractor yard along the US-41 corridor, your building, inventory, and equipment represent real capital that a single covered loss can threaten. Commercial property insurance may help pay to repair or replace covered building property, inventory, and equipment after an eligible direct physical loss. The policy form, exclusions, limits, valuation, and deductible determine what is paid; flood and storm surge commonly require separate consideration. Ellie Insurance Group's Brooksville office shops more than 100 carrier markets to find terms suited to your operation.
Commercial property coverage extends well beyond the four walls of a structure. A well-structured policy addresses business personal property, inventory, tenant improvements you have installed in a leased space, and the income your operation loses while repairs are underway. Many commercial leases and lenders require evidence of property coverage before you open your doors or close a loan, so having the right limits in place is both a practical and contractual necessity. Licensed agent Kevin Smith works with Hernando County businesses across every major submarket to match coverage structure to the specific risks contractors, retailers, marine-adjacent operators, and service firms actually carry.
Your business and location
What to consider for commercial property in Brooksville
Nature Coast property underwriting is driven by wind exposure, roof age, and flood zone classification in ways that affect Hernando County businesses more directly than inland markets. Roof age and condition can affect commercial-property eligibility, price, valuation, and deductible options. There is no single statewide 15- or 25-year commercial roof rule; review the proposed insurer's requirements for this building and roof., and coastal parcels in Hernando Beach and Aripeka frequently require separate wind deductibles and surplus-lines markets. Check the specific address on FEMA's Flood Map Service Center and Hernando County's mapping resources; map amendments or revisions can affect the result. Flood coverage is a risk decision for many businesses and may be required when property in an identified special flood hazard area secures specified federal financial assistance. Your lender and lease can impose additional requirements. Light-industrial and contractor properties along US-41 and SR-50 face their own contents and equipment valuation scrutiny given the tools and materials stored on-site.
Illustrative scenario
When a Storm Interrupts a Nature Coast Service Operation
Consider a service business operating out of a leased commercial bay near the US-41 corridor that sustains wind damage to its roof during a named storm. The structure requires temporary boarding, then full roof replacement, and interior equipment is damaged by water intrusion before repairs are complete. If wind damage is a covered cause of loss, the loss exceeds the deductible, and the relevant limits and endorsements apply, the policy may pay eligible damage to covered tenant improvements and equipment. Business-income and extra-expense coverage may address qualifying financial loss and necessary extra expense during the policy's period of restoration. Water damage caused by flood or storm surge would need separate flood analysis. Without that layered structure, the owner absorbs each of those costs independently — a combination that strains even well-capitalized small firms.
Example for illustration only. Coverage depends on your policy's terms, limits, and exclusions.
Commercial Property coverage
What commercial property insurance covers in Brooksville
- Buildings and structures you own or improve
- Business personal property, inventory, and equipment
- Business income / extra expense after a covered loss
- Tenant improvements and betterments
- Equipment breakdown (with endorsement)
Brooksville considerations
Local factors that affect your commercial property program
- Florida construction WC
Construction businesses with one or more employees generally need workers' compensation; requirements for contractors you hire depend on Florida law and the contract.
- Wind and roof age
Nature Coast property pricing reflects wind exposure and roof-age thresholds.
- Rural radius auto
Service and contractor fleets cover wide rural territory across Hernando and Pasco.
- Flood zones
Coastal and low-lying Hernando properties often need separate flood coverage.
Brooksville · Commercial Property
An Ellie agent in your corner
Get help comparing commercial property insurance for your Brooksville business. We shop multiple markets for competitive quotes and explain your choices in plain language.
More Brooksville coverage
Other commercial policies for Brooksville businesses
Brooksville General Liability
Help protect your business when a customer is injured or your work damages someone else’s property.
Learn more
Brooksville Workers' Compensation
Help employees recover from work injuries and protect your business with workers’ compensation insurance.
Learn more
Brooksville Commercial Auto
Insurance for work trucks, service vans and fleets—built around the driving your business does.
Learn more
Verified Google Reviews
5.0★ on Google · read every review at the source
Google supplies the rating and selected review content when available. Visit Google to see the current rating and all reviews.
5.0★ on Google
Read every verified review directly on Google — we don't post curated testimonials on this site.
FAQ
Frequently Asked Questions
- Standard commercial property forms typically cover wind as a named peril, but coastal Hernando County properties — particularly those in Hernando Beach and Aripeka — often require a separate wind deductible applied specifically to hurricane events. Some properties in high-exposure zones must be placed in specialty or surplus-lines markets rather than standard admitted carriers. Ellie's Brooksville office reviews your property's location, construction type, and roof age to identify which markets will write the coverage and on what terms, so you understand your actual out-of-pocket exposure before a storm hits.
- Yes. Even without building ownership, a Downtown Brooksville tenant typically needs coverage for business personal property, inventory, and any tenant improvements or betterments installed in the space — shelving, lighting, built-out counters, and similar upgrades. Most commercial leases in Hernando County also contractually require tenants to carry property coverage, and lenders financing business assets often impose the same condition. A policy structured for a tenant looks different from one written for a building owner, and Ellie can help you identify the right coverage limits and form for your specific lease arrangement.
- Most standard commercial-property policies exclude flood, including storm surge, so compare separate NFIP and private flood options when the property has flood exposure or a lender/contract requires coverage. Check building and contents limits separately, deductibles, valuation, the number of buildings insured, and whether the flood option covers any income loss; NFIP commercial flood coverage is limited to direct physical flood damage and does not cover business interruption. Coverage may be available through the National Flood Insurance Program or through private flood markets, depending on your property's flood zone designation and coverage needs. Because flood zone mapping affects both availability and structure, reviewing your property's FEMA designation is an important early step before binding any commercial property program.
- Compare insurance for the building, inventory and equipment your business relies on every day. For Brooksville businesses, the exact coverage depends on the policy form, limits, deductibles, endorsements, and exclusions selected.
- Florida businesses that own or lease a building, hold inventory, or rely on equipment. Property requirements are also written into most commercial leases and loans.
- Commercial Property pricing in Brooksville reflects the business class, size, payroll or sales, prior claims, and Florida-specific factors. Roof age, material, condition, inspection findings, wind features, location, and insurer rules can affect commercial-property terms; homeowner roof-age rules do not create a commercial cutoff. Coastal counties often need separate wind deductibles and specialty markets. The most accurate way to know your cost is an Instant Quote across 100+ carrier markets.
- Roof age, material, condition, inspection findings, wind features, location, and insurer rules can affect commercial-property terms; homeowner roof-age rules do not create a commercial cutoff. Coastal counties often need separate wind deductibles and specialty markets.
- Yes. As an independent agency we shop 100+ carrier markets for commercial property insurance, including admitted and specialty markets when an account does not fit a single carrier's appetite. Brooksville is part of our core Florida service area.
Keep reading
Explore related coverage
Brooksville Commercial Insurance
Explore insurance options for your Brooksville business.
Florida Commercial Insurance
Statewide Florida commercial markets.
Instant Quote
Start an Instant Quote for a Brooksville business.
Commercial Property (Coverage Hub)
How commercial property insurance works and what it covers.
Brooksville General Liability
Help protect your business when a customer is injured or your work damages someone else’s property.
Brooksville Workers' Compensation
Help employees recover from work injuries and protect your business with workers’ compensation insurance.
Carrier access
More insurance options. One agency in your corner.
With access to 100+ carrier markets, we do the shopping so you don’t have to contact each company yourself. Your Ellie agent helps you compare competitive quotes and choose insurance for the work you do.
+75 more
Next step
Let's find insurance for your business
Tell us about your business. We’ll shop our insurance markets for competitive quotes and help you compare coverage, price and the support you need from your agency.